Advanced Financial Modeling Strategies: Architecting Institutional-Grade Models for Strategic Decision-Making
Financial modeling sits at the intersection of accounting precision, corporate finance theory, and software engineering. While foundational models rely on static historical extrapolations and rigid formulas, institutional-grade financial modeling demands dynamic architecture, probabilistic risk assessment, and bulletproof auditability. Whether you are valuing a cross-border acquisition, structuring project finance debt tranches, or stress-testing a SaaS enterprise’s runway under volatile macroeconomic conditions, basic spreadsheet mechanics quickly collapse under complexity.
Moving from competent modeler to financial architect requires abandoning brittle spreadsheet habits in favor of standardized structural discipline, dynamic scenario engines, and stochastic forecasting. Below is an exhaustive framework covering the advanced financial modeling strategies used by elite investment banking teams, private equity associates, and strategic FP&A leaders.
1. Architectural Foundations and Design Philosophy
Before writing a single formula, an advanced modeler establishes the structural blueprint. Poor architecture is the primary reason models break during live executive sessions or due diligence reviews.
The FAST and SMART Standards
Institutional modeling relies on strict design standards—most notably the FAST Standard (Flexible, Appropriate, Structured, Transparent) and SMART methodologies. Every workbook should adhere to four non-negotiable structural rules:
Separation of Concerns: Never mix inputs, calculations, and outputs on the same worksheet. Hardcoded assumptions belong exclusively in dedicated input tabs (styled in blue font), calculation engines reside in intermediate tabs (black font), and executive dashboards pull cleanly from calculation outputs (green font for cross-sheet links).
Left-to-Right Time Consistency: Every single time-series worksheet must share identical column structures. If Column G represents FY2026 on the Income Statement tab, Column G must represent FY2026 on the Balance Sheet, Cash Flow Statement, Debt Schedule, and Working Capital tabs. Consistent column alignment eliminates cross-sheet reference errors and allows formulas to be dragged uniformly across hundreds of rows.
The Rule of Formula Simplicity: Avoid deeply nested
IFstatements or 400-character mega-formulas. If a calculation requires multiple logical conditions, break it into discrete intermediate helper rows. A model that takes ten lines to calculate a complex waterfall is infinitely superior to a single opaque formula that no auditor can trace under pressure.No Hardcodes Inside Formulas: Embedding a constant inside a calculation (e.g.,
=B12*0.21for a tax rate) creates hidden landmines. Every assumption, conversion factor, or tax rate must live in its own labeled assumption cell.
Modular Architecture vs. Monolithic Sheets
As corporate models scale to incorporate multiple business units, currencies, or product lines, monolithic worksheets become sluggish and error-prone. Advanced modelers use modular architecture:
Control & Cover Tab: Contains version history, color-coding legends, model checks summary, and the master scenario switch.
Assumptions & Drivers Tab: Houses macroeconomic inputs, revenue drivers, unit economics, tax rates, and financing terms.
Revenue & COGS Sub-Schedules: Granular cohort-based, price-volume-mix, or capacity-driven operational engines.
Operating Expenses & Headcount Module: Department-level fixed and variable cost drivers tied to headcount productivity and inflation indices.
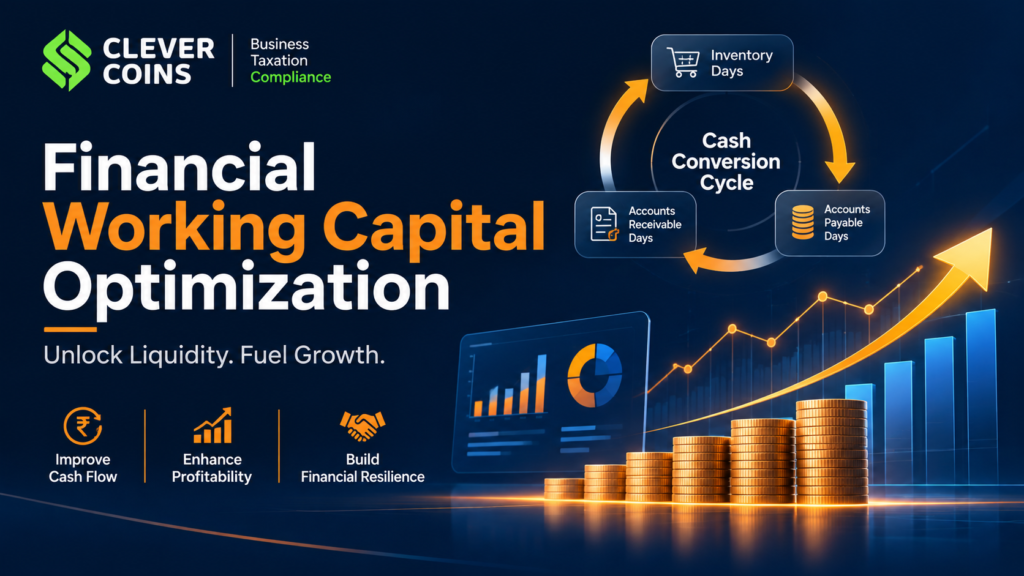
Working Capital & CapEx Schedules: Detailed aging schedules for receivables/payables and depreciation waterfalls for existing versus growth capital expenditures.
Debt & Equity Financing Schedule: Multi-tranche debt waterfalls, revolver mechanics, interest rate sweeps, and share count dilution tables.
Core Three Financial Statements: Clean, uncrowded Income Statement, Balance Sheet, and Cash Flow Statement pulling directly from supporting schedules.
Valuation & Outputs Tab: DCF engine, trading/transaction comps summary, LBO returns matrix, and executive sensitivity tables.
2. Advanced Three-Statement Integration and Circularity Control
Linking the Income Statement, Balance Sheet, and Cash Flow Statement is standard practice, yet handling dynamic edge cases—such as revolvers, cash sweeps, and circular interest calculations—separates advanced practitioners from novices.
Mastering the Debt Sweep and Revolver Mechanics
In leveraged buyouts (LBOs) and corporate liquidity models, excess cash flow automatically pays down senior debt, while cash deficits automatically draw upon a Revolving Credit Facility (Revolver). Building a dynamic cash sweep requires precise logic:
Cash Available for Debt Service (CADS): Start with Operating Cash Flow minus Capital Expenditures and mandatory principal amortization. Ensure you adjust for minimum cash balance requirements—companies cannot sweep their entire bank balance to zero without triggering operational liquidity failure.
Revolver Draw/Paydown Logic: Use
MINandMAXfunctions rather than nestedIFstatements. For example, a dynamic revolver paydown formula looks like:If CADS is negative, the company draws on the revolver up to its maximum commitment limit, triggering an automatic covenant breach flag if the draw exceeds available credit capacity.
Tranche Priority Waterfall: Structure voluntary prepayments sequentially based on seniority and prepayment penalties—typically paying down the Revolver first, followed by Term Loan A, Term Loan B, and subordinated notes (which often prohibit voluntary prepayment or carry make-whole premiums).
Taming Circular References Safely
Circularity arises naturally in corporate finance because Interest Expense depends on Average Debt, which depends on Ending Debt, which depends on Ending Cash, which depends on Net Income, which itself depends on Interest Expense.
While enabling Excel’s iterative calculation engine solves circularity mathematically, uncontrolled circularity can cause models to diverge into #DIV/0! or #VALUE! errors that infect the entire workbook. Advanced modelers deploy two safeguards:
The Circuit Breaker Switch:If a formula error causes the iterative loop to blow up, toggling the switch to
0immediately resets all debt and cash balances to clean non-circular values, allowing you to restore it to1once the underlying input is corrected.Beginning-of-Period Approximation: For early-stage strategic models or high-frequency simulations (such as Monte Carlo runs), calculate interest based strictly on Beginning Debt and Beginning Cash balances. Eliminating circularity altogether dramatically increases calculation speed and guarantees deterministic convergence.
3. Dynamic Scenario, Sensitivity, and Simulation Engines
A single deterministic forecast is guaranteed to be wrong. Executives do not need a single point estimate; they need to understand the distribution of potential outcomes and identify which operational levers carry the highest asymmetry.
Multi-Dimensional Scenario Managers
Instead of building separate workbooks for Base, Bull, and Bear cases, construct a unified Scenario Manager using INDEX/MATCH or CHOOSE functions driven by a single active scenario integer (1, 2, or 3).
Granular Driver Overrides: Allow each scenario to toggle independent operational assumptions—such as customer churn rate, gross margin expansion, working capital days, and exit multiples—rather than applying blunt top-line percentage hair-cuts.
Custom Flex Case: Always include a fourth “Custom / Management Flex” column in your scenario table. During live board meetings, leadership can type ad-hoc assumptions into the Custom column without overwriting validated Base, Upside, or Downside benchmarks.
Two-Way Data Tables and Dynamic Heatmaps
Excel’s native Data Table recalculates an entire model across a matrix of two independent variables—such as Weighted Average Cost of Capital (WACC) versus Terminal Growth Rate, or Revenue CAGR versus EBITDA Margin.
Performance Optimization: Data tables are computationally heavy and can slow down large workbooks. Set workbook calculation mode to “Automatic Except for Data Tables” so routine edits remain instantaneous, refreshing data tables only when pressing
F9.Conditional Formatting Heatmaps: Apply subtle three-color conditional formatting gradients (red-white-green) across sensitivity matrices to highlight valuation inflection points and covenant breach zones immediately.
Monte Carlo Simulation in Financial Modeling
When multiple variables fluctuate simultaneously with differing probability distributions, deterministic sensitivity tables fall short. Monte Carlo simulation runs thousands of randomized trials to map the full probability distribution of key outputs like Net Present Value (NPV), Internal Rate of Return (IRR), or cash runway.
Assign Probability Distributions to Key Drivers: Instead of static inputs, define statistical distributions for uncertain variables.
Triangular or PERT Distributions for project timelines, capex overruns, or drug trial success probabilities where minimum, most likely, and maximum bounds are known.
Lognormal Distribution for commodity prices or asset values that cannot fall below zero and exhibit right-skewness.
Incorporate Variable Correlation: Independent random draws distort reality—for example, revenue growth and inflation or raw material costs often move together. Use a Cholesky decomposition matrix to correlate random normal draws across dependent drivers so simulated scenarios remain economically coherent.
Analyze Tail Risk (VaR and CVaR): Extract the 5th percentile (Value at Risk) and the average of the worst 5% of outcomes (Conditional Value at Risk) from your simulation output table to quantify downside exposure rigorously.
4. Granular Revenue, Unit Economics, and Cohort Modeling
Top-down forecasting (“Market size is $50B, and we will capture 1% by Year 5”) is rejected immediately by sophisticated investors. Advanced financial models build revenue from the bottom up using verifiable operational mechanics.
SaaS and Subscription Cohort Waterfalls
For recurring revenue businesses, aggregate customer counts mask underlying churn dynamics. Build a triangular Cohort Retention Matrix:
Monthly/Annual Acquisition Cohorts: Track each group of newly acquired customers horizontally across time periods. Apply non-linear retention curves—recognizing that customer churn is typically highest in months 1 through 3 before flattening into a steady-state expansion phase.
Net Dollar Retention (NDR) Decomposition: Model gross logo churn, contraction (downgrades), and expansion (upsells and seat additions) separately. True institutional models differentiate between Gross Revenue Retention (capped at 100%) and Net Revenue Retention (which can exceed 120%+ in best-in-class enterprise software).
CAC Payback and LTV/CAC Dynamics: Link Sales & Marketing headcount and paid acquisition spend directly to new customer additions via lagged conversion funnels, dynamically computing Customer Acquisition Cost (CAC) payback periods in months.
Price-Volume-Mix (PVM) Bridges
In manufacturing, retail, and consumer packaged goods, top-line growth must be decomposed into three distinct drivers:
Modeling PVM explicitly prevents analysts from confusing inflationary price hikes with genuine market share volume gains, and reveals how shifts toward lower-margin SKUs compress blended gross margins even when total revenue rises.