
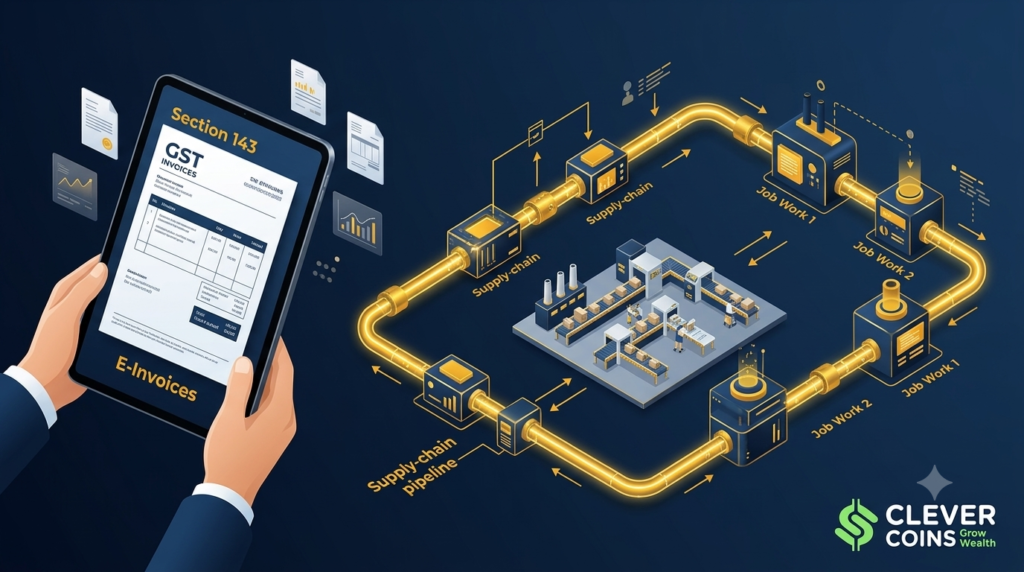
Comprehensive Guide to Job Work Provisions Under GST Section 143
Introduction to Job Work Under GST
In modern manufacturing and commerce, businesses rarely execute every single stage of production under one roof. Outsourcing specific manufacturing processes, treatments, or refinements to specialized third-party artisans, fabricators, or processing units is standard practice. Under the Goods and Services Tax (GST) regime, this specialized framework is formally recognized as Job Work.
At the center of this legislative mechanism sits Section 143 of the Central Goods and Services Tax (CGST) Act, 2017. Section 143 provides a special procedure that allows registered taxpayers—referred to as principals—to send inputs and capital goods to job workers without immediately triggering tax liabilities. This provision acts as a vital economic bridge, preventing severe cash-flow blockages for manufacturing and supply chain networks across India.
Core Definition: What is Job Work and Who is a Principal?
To master compliance under Section 143, one must understand the statutory terminology defined within the CGST Act:
-
Job Work (Section 2(68)): Any treatment or process undertaken by a person on goods belonging to another registered taxable person (the principal). In simpler terms, transforming or working on raw goods owned by someone else makes the activity a job work process. The person executing this work is the Job Worker.
-
Principal (Section 2(94) read with Section 143): A registered person under GST who sends their inputs, semi-finished goods, or capital goods out to a job worker for further processing, assembly, testing, or completion.
Crucially, the law treats the job worker as an extension of the supply chain rather than an independent commercial owner of those specific goods during the processing phase, provided proper procedural compliances are met.
Key Mechanics of Section 143(1): Movement of Goods Without Tax
Under Section 143(1), a registered principal is granted the statutory permission to send inputs, semi-finished goods, or capital goods to a job worker without payment of tax. However, this movement is subject to specific administrative conditions and prior intimation via documentation rules (primarily Rule 45).
1. Movement of Inputs
-
Definition Scope: Under the explanation to Section 143, “inputs” include intermediate goods arising from any treatment or process carried out on the inputs by either the principal or the job worker.
-
No Tax at Dispatch: When inputs leave the principal’s factory floor toward a job worker, no GST is payable, protecting operational liquidity.
2. Movement of Capital Goods
-
Inclusion: Capital goods, machinery components, and equipment can similarly be sent to job workers for specialized repairs, calibration, or operational utilization.
-
Exclusion from Return Mandate: Notably, tools, dies, moulds, and fixtures sent to a job worker are explicitly exempted from the mandatory return timelines that apply to standard capital goods and inputs.
Mandatory Time Limits for Return or Direct Supply
Goods cannot remain indefinitely at a job worker’s facility without definitive tracking. Section 143 establishes strict temporal boundaries within which goods must either return to the principal or be cleared commercially:
-
For Inputs: Inputs sent to a job worker must be brought back to any of the principal’s places of business or supplied directly from the job worker’s place of business within 1 year of being sent out.
-
For Capital Goods: Capital goods (excluding moulds, dies, jigs, fixtures, and tools) must be returned or supplied directly within 3 years of being sent out.
Extension of Time Limits
If genuine operational hardships or business delays occur (such as protracted engineering timelines or specialized multi-stage processing), the Commissioner is empowered under the law to extend these periods upon sufficient cause being shown:
-
Inputs can be extended by a further period not exceeding 1 year (Total: 2 years).
-
Capital goods can be extended by a further period not exceeding 2 years (Total: 5 years).
Options Available Upon Completion of Job Work
Once the job worker completes the mandated process, the principal has three distinct legal pathways to dispose of or account for the goods:
Option A: Bringing Goods Back
The principal can bring the inputs, intermediate goods, or capital goods back to their primary place of business or any registered additional place of business without paying tax.
Option B: Direct Supply from Job Worker’s Premises
The principal may supply the finished or processed goods directly from the job worker’s premises to domestic buyers or for export.
-
Crucial Condition: Under the first proviso to Section 143(1), the principal can only supply goods directly from the job worker’s place of business if that specific place of business is declared as an additional place of business by the principal.
-
Exceptions to Declaration: Declaring the job worker’s premise as an additional place of business is not required if:
-
The job worker is registered under Section 25 independently under GST; or
-
The principal is engaged in supplying notified categories of goods as notified by the Commissioner.
-
Option C: Supply of Waste and Scrap (Section 143(5))
During manufacturing and job work processes, waste and scrap are inevitably generated. Under Section 143(5):
-
If the job worker is registered, the waste and scrap can be supplied directly from their premises upon payment of applicable tax.
-
If the job worker is unregistered, the waste and scrap must be cleared, accounted for, and taxed directly by the principal.
Accountability, Records, and Documentation (Rule 45)
Compliance under Section 143 is heavily dependent on paper trails and electronic accountability.
1. Responsibility for Accounts (Section 143(2))
The legal responsibility for maintaining proper, audit-ready accounts and records for all inputs and capital goods sent to, held by, or returned from job workers lies entirely with the principal. Even if physical custody rests with multiple tier-1 and tier-2 job workers, the tax accountability remains anchored to the principal.
2. The Challan System (Rule 45(1))
Every movement of goods—whether from the principal to the job worker, from one job worker to another, or back to the principal—must be accompanied by a pre-numbered delivery challan.
-
The challan must contain all prescribed particulars under Rule 45(2) (such as HSN codes, description, quantity, tax values, and GSTIN details).
-
Endorsement Facility: If goods move from Job Worker A to Job Worker B, the original challan issued by the principal can be endorsed by Job Worker A, and subsequently by Job Worker B, ensuring unbroken traceability across multi-tier supply chains.
3. Statutory Filing: Form GST ITC-04
To maintain structural transparency, principals are required to file Form GST ITC-04. This is a specialized electronic return detailing all challans for inputs and capital goods dispatched to job workers, received back, or supplied from job worker locations during the reporting period.
-
Historically filed on a half-yearly or yearly basis depending on turnover thresholds, ITC-04 remains a critical audit focal point during departmental scrutiny.
Consequences of Non-Compliance: What Happens If Goods Are Not Returned?
Failure to bring back goods within the stipulated 1-year (inputs) or 3-year (capital goods) windows triggers severe legal consequences under Sections 143(3) and 143(4):
-
Deemed Supply Fiction: If inputs or capital goods are not returned or directly supplied within the statutory timeline, it is legally deemed that such goods were supplied by the principal to the job worker on the very day the goods were originally sent out.
-
Tax Liability and Interest: The principal becomes liable to pay the applicable GST on those unreturned goods, alongside mandatory interest calculated from the date of initial dispatch.
-
Input Tax Credit (ITC) Reversal Risk: Failure to reconcile job work movements frequently invites tax audits, demand notices under Section 73/74, and potential penalties for suppression of turnover.
Strategic Tax Planning and Best Practices for Businesses
To safeguard your organization against avoidable tax disputes, interest liabilities, and audit friction, financial consultants recommend implementing the following standard operating procedures:
-
Maintain Real-Time Reconciliations: Do not wait until the annual filing window to match challans. Implement automated ERP trackers linking dispatch challans with receipt challans.
-
Audit Job Worker Premises: Conduct periodic physical inventory audits at vendor/job worker facilities to verify that stock levels match digital records.
-
Proactively Register Additional Places of Business: If utilizing dedicated long-term job workers who are unregistered, ensure their premises are formally added as additional places of business on your GST portal to legally clear direct supplies.
-
Partner with Tax Professionals: Complex multi-state manufacturing chains require specialized structuring. Leverage expert advisory platforms like CleverCoins to navigate compliance seamlessly, optimize indirect taxation, and protect your bottom line.
- Phone: +91 77389 59862
- Email: client@clevercoins.org
- Address: Ideal Market, Mumbra, Thane-400612





