
Mandatory GST Registration Thresholds: Goods vs. Services Limits Explained
Navigating the tax landscape of the Goods and Services Tax (GST) regime in India can feel like threading a needle in the dark. For startup founders, freelancers, small business owners, and corporate consultants alike, one of the most critical compliance questions asked is: “When do I officially need to register for GST?”
The answer is not a single blanket number. Instead, the Indian indirect tax structure sets distinct operational boundaries, drawing a clear line between the supply of goods and the supply of services. Misinterpreting these limits can lead to severe penalties, frozen accounts, or missed opportunities for legitimate tax credits.
Brought to you by the tax advisory experts at Clever Coins, this exhaustive guide breaks down everything you need to know about mandatory GST registration thresholds, the core differences between goods and services limits, state-specific variations, mandatory registration triggers, and how to calculate your aggregate turnover accurately.
Understanding the Foundation: What is GST Aggregate Turnover?
Before diving into the specific monetary caps, it is vital to understand how the government measures whether you have crossed the line. The law does not look at your net profit, nor does it look merely at your primary product line. It looks at your Aggregate Turnover on a PAN-India basis.
What is Included in Aggregate Turnover?
To determine if you have breached the threshold, you must aggregate the value of all supplies made under the same Permanent Account Number (PAN) across the country:
Taxable Supplies: All standard sales of goods and services subject to GST.
Exempt Supplies: Goods or services that do not attract GST or are explicitly exempted.
Export of Goods and Services: International outbound shipments or services rendered globally (treated as zero-rated supplies).
Inter-State Supplies: Transfers or sales made from one state to another under the same PAN.
Supplies on behalf of Principals: Transactions executed by an agent on behalf of a principal.
What is Excluded from Aggregate Turnover?
Central Tax (CGST), State Tax (SGST), Union Territory Tax (UTGST), Integrated Tax (IGST), and Cess.
Inward supplies on which tax is paid under the Reverse Charge Mechanism (RCM).
Core Threshold Limits: Goods vs. Services
The distinction between trading physical commodities and rendering intellectual or physical services forms the bedrock of registration exemptions.
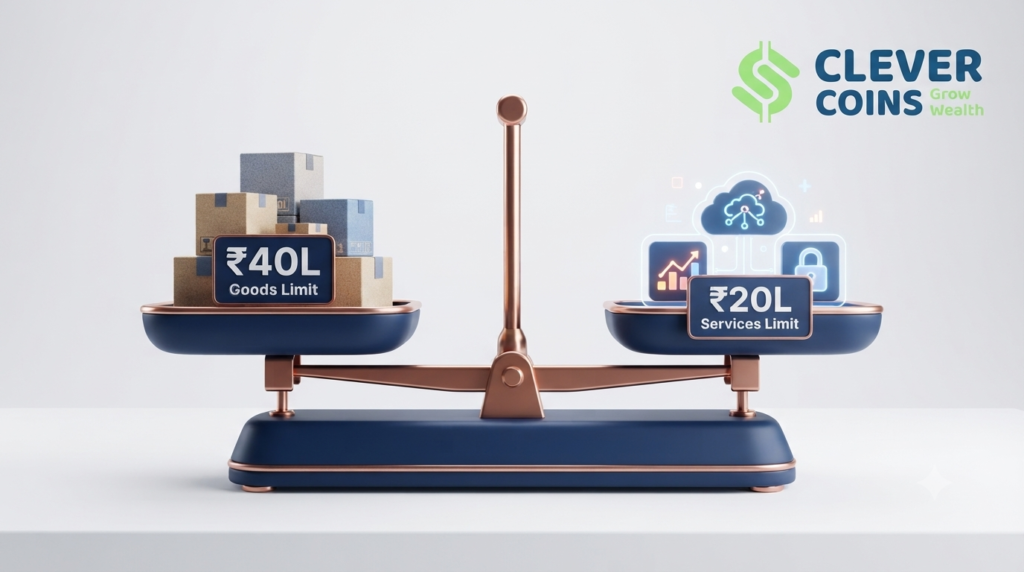
1. The Threshold for Goods: ₹40 Lakhs
For businesses exclusively engaged in the supply of goods, the threshold limit for mandatory registration is ₹40 Lakhs annual aggregate turnover in normal category states.
The Logic: Introduced to ease the compliance burden on small traders, micro-retailers, and manufacturers, this higher limit ensures that smaller localized merchants do not get entangled in complex monthly return filings.
Crucial Caveat: This ₹40 lakh limit is not unconditional. It applies only if the state has opted for it and the business does not fall under specific restricted categories.
2. The Threshold for Services: ₹20 Lakhs
For entities engaged in supplying services (or a mix of goods and services where service components dominate), the threshold remains fixed at ₹20 Lakhs.
The Logic: Service providers—ranging from IT consultants and digital marketing agencies to freelance designers and legal advisors—operate under a stricter standard. Unlike the goods threshold, the ₹20 lakh service threshold is uniform across regular category states.
State-Wise Classification: Normal vs. Special Category States
India’s federal tax structure categorizes states differently based on geographic, economic, and historical considerations. The thresholds shift dramatically depending on where your principal place of business is located.
Normal Category States (Goods: ₹40L | Services: ₹20L)
Most major states and union territories fall into this bracket, including Maharashtra, Delhi, Karnataka, Tamil Nadu, Uttar Pradesh, Gujarat, Andhra Pradesh, and West Bengal. In these regions, goods suppliers enjoy the ₹40 lakh cap, while service providers operate under the ₹20 lakh cap.
Special Category States (Lower Thresholds Apply)
Certain northeastern and hilly states have historically lower thresholds to accommodate unique local economic structures.
The ₹10 Lakh Limit: States like Mizoram, Tripura, Manipur, and Nagaland enforce a much lower aggregate turnover threshold of ₹10 Lakhs for both goods and services.
The ₹20 Lakh Special Limit: Some states like Jammu & Kashmir, Assam, and Himachal Pradesh maintain specialized rules where thresholds align closer to ₹20 lakhs for certain categories.
Pro Tip from Clever Coins: Always evaluate your multi-state operations carefully. If you have active branches or warehouses across multiple state borders, you may be required to secure separate state-wise GST registrations regardless of whether your overall turnover is relatively modest.
Exceptions Where the ₹40 Lakh Goods Limit Does NOT Apply
Many business owners mistakenly assume that any goods business is safe up to ₹40 lakhs. The law outlines strict exclusions where you lose the privilege of the higher goods threshold and must register once you cross ₹20 Lakhs (or even from rupee one in specific scenarios):
Inter-State Supply of Goods: If you procure materials or sell goods across state lines, the ₹40 lakh exemption instantly vanishes, and you are bound by normal registration triggers.
Notified Goods Categories: Businesses dealing in specific items—such as ice cream and other edible ice (whether or not containing cocoa), pan masala, and tobacco or manufactured tobacco substitutes—are explicitly barred from utilizing the ₹40 lakh limit.
Persons Required to Pay Tax under RCM: If your business model forces you to discharge tax liabilities under the Reverse Charge Mechanism for certain inward supplies, special care must be taken.
Casual and Non-Resident Taxable Persons: Individuals executing temporary business operations in states where they have no fixed place of business cannot leverage standard thresholds.
Mandatory GST Registration Regardless of Turnover Thresholds
Crossing the monetary turnover limits (₹20L or ₹40L) is not the only trigger for registration. Under Section 24 of the CGST Act, certain business models and activities require mandatory registration from day one, irrespective of your financial turnover:
Inter-State Taxable Supplies: Making any outward taxable supply from one state to another automatically triggers compulsory registration.
E-Commerce Operators and Aggregators: Companies that own, operate, or manage digital platforms facilitating supplies (like Amazon, Flipkart, or specialized service marketplaces) must register unconditionally.
Suppliers Selling Through E-Commerce: If you sell physical goods or services through electronic commerce operators who collect Tax Collected at Source (TCS), registration is compulsory (with minor exceptions for intra-state goods suppliers meeting specific composition criteria).
Casual Taxable Persons (CTP): Individuals or entities occasionally undertaking transactions involving supply of goods or services in a state where they have no fixed permanent business establishment.
Non-Resident Taxable Persons (NRTP): Foreign entities or individuals residing outside India who occasionally supply goods or services to recipients within India.
Tax Deduction at Source (TDS) Deductors: Government departments, public sector undertakings, or notified authorities required to deduct tax under Section 51.
Input Service Distributors (ISD): Offices receiving tax invoices for common input services intended for distribution to distinct units under the same PAN.
Online Money Gaming Providers: Entities supplying online money gaming services from a location outside India to individuals residing inside India.
Voluntary GST Registration: When Should You Register Early?
If your turnover is hovering around ₹10 lakhs or ₹15 lakhs and you provide services, or if you are trading goods below ₹30 lakhs, is it smart to stay unregistered? Not always. Voluntary GST Registration offers massive strategic advantages that can supercharge your business growth:
Claiming Input Tax Credit (ITC): When you purchase raw materials, software, office supplies, or machinery, you pay GST on those purchases. Without a GST registration, this tax is a permanent cost. Registering voluntarily allows you to claim ITC, substantially reducing your effective operational costs.
Seamless B2B Transactions: Large corporate clients and registered companies prefer dealing with GST-compliant vendors because it keeps their own ITC chains unbroken. Being unregistered can cause corporate clients to turn away due to their own compliance fears regarding reverse charge mechanisms or reporting gaps.
Inter-State Expansion: Voluntary registration allows you to scale nationwide, pitch to clients across state borders, and list your products on major e-commerce platforms without administrative roadblocks.
Enhanced Brand Credibility: A GSTIN (Goods and Services Tax Identification Number) printed on your invoices builds instant trust, projecting your enterprise as an established, legally compliant entity.
Penalties for Non-Compliance and Late Registration
Ignoring GST registration mandates is a high-stakes gamble. According to Section 122 of the CGST Act, if a taxable person who is liable to secure registration fails to do so, the penalties are severe:
The Base Penalty: The offender must pay a penalty amounting to 10% of the tax due subject to a minimum floor limit of ₹10,000.
Intentional Evasion: If authorities determine that tax evasion was deliberate and fraudulent, the penalty scales up to 100% of the tax evaded, alongside potential asset seizure, legal scrutiny, and prosecution.
Step-by-Step Overview of the GST Registration Process
Once you cross your respective threshold limit or trigger a mandatory clause, you must apply for registration within 30 days of becoming liable.
Part-A (TRN Generation): Access the official GST portal, submit your PAN, mobile number, and email address. Authenticate via OTP to receive a Temporary Reference Number (TRN).
Part-B (Detailed Application): Log in using the TRN, complete the detailed application form, and upload core business documents (PAN card, business constitution proof, photographs of promoters, bank account details, and registered address proof like electricity bills or lease agreements).
Application Reference Number (ARN): Submit the application using a Digital Signature Certificate (DSC) or Electronic Verification Code (EVC) to receive your ARN.
Officer Verification & Approval: Tax authorities inspect the submission. If found compliant, the official GSTIN certificate is issued, usually within 3 to 7 working days.
Conclusion: Let Clever Coins Secure Your Tax Strategy
Navigating aggregate turnovers, differentiating between intra-state and inter-state supplies, and evaluating whether your specific product line falls under restricted categories requires acute attention to detail. Staying ahead of regulatory shifts prevents costly penalties and unlocks structural tax efficiencies.
At Clever Coins, we turn complex tax codes into strategic advantages for your bottom line. Whether you are evaluating your threshold limits, setting up new business verticals, or executing seamless GST filings, our dedicated team of tax consultants acts as your proactive financial partner.
Stop reacting to tax season—start navigating it with a partner dedicated to making every coin count. Contact Clever Coins today for a comprehensive GST health check and registration consultation.
- Phone: +91 77389 59862
- Email: client@clevercoins.org
- Address: Ideal Market, Mumbra, Thane-400612





