
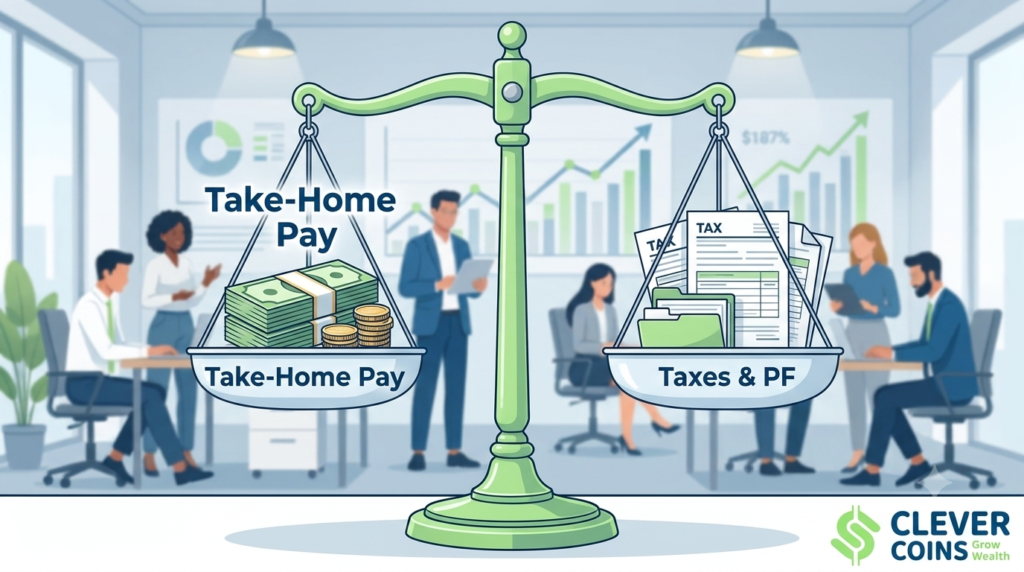
Salary Structuring for Startups: Maximizing In-Hand Pay While Minimizing Tax & PF Liability
Attracting top talent is one of the biggest hurdles for early-stage startups. While large corporations can lure candidates with massive fixed compensations, startups must rely on equity, growth potential, and—most importantly—a highly optimized salary structure. A poorly designed Cost to Company (CTC) package can result in a significant portion of an employee’s salary being swallowed by taxes and statutory deductions, leaving them dissatisfied with their monthly take-home pay.
Designing an efficient compensation structure requires balancing employee satisfaction with stringent statutory compliance. This comprehensive guide breaks down the core components of Indian payroll, tax optimization strategies, Provident Fund (PF) management, and how to structure a startup compensation package that maximizes in-hand pay without inviting regulatory penalties.
The Anatomy of CTC: Decoding the Jargon
Before optimizing a salary structure, it is crucial to understand the distinct layers of compensation. Candidates often confuse CTC with their take-home pay, leading to mismatched expectations upon receiving their first paycheck.
Cost to Company (CTC): The total monetary value an employer spends on an employee annually. This includes fixed pay, variable bonuses, statutory contributions (like employer PF and Gratuity), and the monetary value of perks or benefits.
Gross Salary: The total earnings of an employee before any deductions like income tax or employee PF contributions are applied. It is calculated by adding basic salary and all allowances.
HONONet Salary (Take-Home Pay): The final amount credited to the employee’s bank account after deducting Tax Deducted at Source (TDS), Professional Tax (PT), and Provident Fund (PF).
An ideal salary structure minimizes the gap between the Gross Salary and the Net Salary while keeping the CTC competitive and fully compliant with Indian labor and tax laws.
Core Salary Components and Optimization Strategies
A well-structured salary package divides the total compensation into specific heads that leverage tax exemptions.
1. Basic Salary
The basic salary is the foundation of the entire compensation package. All major statutory components, including Provident Fund and Gratuity, are calculated as a percentage of the basic salary.
The Optimization Rule: An ideal structure typically keeps the basic salary between 40% to 50% of the total CTC.
Saral ProThe Risk of Getting it Wrong: If the basic salary is set too high, both the employer and employee face a heavier PF burden, and the employee’s tax liability increases. Conversely, setting the basic salary too low invites scrutiny from labor departments for violating the Minimum Wages Act. Startups must ensure the basic pay strictly complies with state-specific minimum wage laws for skilled and highly skilled workers.
2. House Rent Allowance (HRA)
HRA is a crucial tax-saving tool for employees living in rented accommodations. For startups operating in major tech hubs like Bengaluru, Mumbai, or Delhi, optimizing HRA can drastically reduce a candidate’s tax liability.
Structuring: HRA is generally set at 50% of the Basic Salary for employees in metro cities and 40% for those in non-metro cities.
Saral ProTax Exemption: The tax exemption under Section 10(13A) is calculated as the minimum of the following three:
Actual HRA received.
50% of Basic Salary (metro) or 40% (non-metro).
Actual rent paid minus 10% of the Basic Salary.
3. Leave Travel Allowance (LTA)
LTA is designed to cover travel expenses incurred by an employee and their immediate family while on leave. It is conditionally tax-exempt, provided the travel is within India and the employee submits valid travel proofs (flight or train tickets).
Structuring: Startups usually allocate around 8% to 10% of the basic salary as LTA. If an employee does not travel or submit proofs, the amount is paid out at the end of the financial year but is fully taxable.
4. Special Allowances
Special allowances are fully taxable components used as a “balancing figure” to round out the CTC after all other structured allowances and basic pay have been defined. Because this component is fully taxable, startups should aim to legally minimize this category by allocating funds to tax-exempt reimbursements and perquisites first.
Minimizing Provident Fund (PF) Liability
The Employees’ Provident Fund (EPF) is mandatory for organizations with 20 or more employees. While it serves as an excellent retirement vehicle, mandatory deductions take a heavy toll on immediate cash flow for both the startup (employer contribution) and the young professional (employee contribution). The standard contribution rate is 12% of the Basic Salary plus Dearness Allowance (DA).
Strategies for PF Optimization
The Statutory Wage Ceiling: According to EPF rules, mandatory PF contributions are only required if an employee’s basic salary is ₹15,000 per month or lower. If the basic salary exceeds ₹15,000, the employee and employer have the option to cap the PF contribution at 12% of ₹15,000 (which equals ₹1,800 per month).
Opting Out (For New Employees): If a new hire has never been a member of the EPF scheme and their starting basic salary is above ₹15,000, they can choose to opt out of the PF scheme entirely by filling out Form 11. This instantly boosts the employee’s take-home pay by preventing the 12% deduction and allows the startup to shift the 12% employer contribution into the employee’s gross allowances.
Restricting Employer Contributions: Startups can restrict the employer’s share to the statutory minimum of ₹1,800 per month, even if the employee wishes to contribute a higher percentage (Voluntary Provident Fund) on a larger basic salary.
Utilizing Tax-Exempt Reimbursements & Perquisites
To aggressively maximize in-hand pay, startups should replace a portion of fully taxable “Special Allowances” with structured reimbursements. While these require employees to submit bills, they drastically reduce the taxable income base.
| Reimbursement Type | Exemption Limit & Tax Treatment | Implementation Strategy |
|---|---|---|
| Communication Allowance | Fully exempt upon bill submission | Cover mobile and broadand expenses, vital for remote/hybrid startup teams. |
| Food & Meal Vouchers | Exempt up to ₹50 per meal (approx. ₹2,200 to ₹2,600/month) | Issue prepaid meal cards (e.g., Sodexo, Zeta) rather than cash allowances. |
| Books & Periodicals | Fully exempt upon actual bill submission | Encourage upskilling by covering industry magazines, online courses, or physical books. |
| Gadget/Asset Allowance | Depreciation benefits | Allow employees to purchase laptops/phones through the company, treating the asset depreciation as a corporate expense rather than taxable employee income. |
Designing for the Old vs. New Tax Regime
The introduction of the New Tax Regime requires startups to rethink blanket salary structures. The new regime offers lower baseline tax rates but completely strips away almost all major exemptions, including HRA, LTA, and standard deduction (though the standard deduction of ₹50,000 was recently reintroduced to the new regime).
Employees on the Old Regime: Thrive on a highly fragmented salary structure. They require HRA, LTA, Meal Vouchers, and maximum utilization of Section 80C through PF contributions to lower their tax slab.
Employees on the New Regime: Do not benefit from fragmented allowances. For these employees, a flat structure heavily weighted toward Basic Salary and Special Allowances is simpler, as they will be taxed on the gross amount regardless of how it is categorized.
Best Practice: Implement a flexible benefit plan (FBP). Allow employees to customize their allowance components at the beginning of the financial year based on their declared tax regime.
Variable Pay, ESOPs, and Retention
Startups often cannot match the fixed cash components of enterprise corporations. To bridge the gap, they rely heavily on variable pay and Employee Stock Ownership Plans (ESOPs).
Performance Bonuses: Bonuses are fully taxable in the year they are received. To optimize, startups can structure bonuses as annual or bi-annual payouts to aid in employee retention, though they will invariably increase TDS liabilities.
ESOP Taxation: ESOPs are a dual-taxation instrument in India. Employees are taxed first when they exercise the options (the difference between the Fair Market Value and the exercise price is taxed as a perquisite). They are taxed again when they sell the shares (Capital Gains tax on the difference between the sale price and the FMV).
Startup Exemption: Eligible startups recognized by the DPIIT can defer the tax burden on ESOP perquisites for up to five years, or until the employee leaves the company or sells the shares, whichever is earliest. Registering for this DPIIT exemption is a massive competitive advantage for talent acquisition.
Common Mistakes Startups Make
Ignoring Professional Tax (PT): PT is a state-level tax on salaried income that must be deducted directly from the gross salary. Failing to deduct and remit PT in states like Maharashtra, Karnataka, and Telangana results in severe compliance penalties.
HONOImproper Gratuity Accounting: The Payment of Gratuity Act mandates that companies pay 15 days of wages for every year of completed service to employees who complete five years. Startups often fail to factor this into the CTC calculation, creating an unfunded liability on their balance sheets.
Overloading Basic Salary: Setting basic salary at 70% or 80% of CTC to “keep it simple” results in massive, unnecessary PF drains and higher tax burdens.
Conclusion
Salary structuring is not a simple data entry task; it is a strategic financial lever. By strictly adhering to the 40-50% basic salary rule, capping PF contributions legally, and offering flexible, tax-exempt reimbursement brackets, a startup can legitimately increase an employee’s take-home pay by 10% to 15% without spending an extra rupee. Aligning your compensation strategy with compliance safeguards your business from labor disputes and positions your startup as a sophisticated, employee-centric employer in a highly competitive market.
Related posts:
Maharashtra Professional Tax (PTEC vs PTRC): Applicability, Rates, and Monthly Returns
The Complete Guide to EPFO Registration for Employers: The 20-Employee Threshold, Form 5A, and Shram...
The Complete Guide to Contract Labour Regulation and Abolition Act (CLRA): Registration and Licensin...
ESIC Monthly Contribution and Return Filing: Common Portal Errors and Due Dates
ESIC Registration Thresholds and Benefits: Complete Employer Compliance Roadmap
Handling EPFO Inspection Notices Under Section 7A: Legal Rights and Defense Strategy
The Complete Guide to the Payment of Gratuity Act: Employer Liabilities, Calculation, and Forfeiture...
Related posts:
 The Complete Guide to EPFO Registration for Employers: The 20-Employee Threshold, Form 5A, and Shram Suvidha
 ESIC Registration Thresholds and Benefits: Complete Employer Compliance Roadmap
 ESIC Monthly Contribution and Return Filing: Common Portal Errors and Due Dates
 Maharashtra Professional Tax (PTEC vs PTRC): Applicability, Rates, and Monthly Returns



