Break-Even Analysis Case Study for SMEs: A Practical Guide to Understanding Business Profitability
Introduction
Running a small or medium-sized enterprise (SME) involves more than generating sales and acquiring customers. Business owners must understand how much revenue their company needs to generate to cover its operating expenses, manage financial risks, and achieve sustainable profitability.
Many businesses experience a situation where sales are increasing, customers are purchasing products, and daily operations appear successful, but the business is still struggling to generate meaningful profits.
Why does this happen?
One of the most common reasons is that business owners do not have a clear understanding of their break-even point.
Break-even analysis is one of the most practical financial management tools for SMEs. It helps business owners determine the exact sales volume or revenue required to cover their total costs without generating a financial loss or profit.
For startups, it helps evaluate whether a business idea is financially viable. For established SMEs, it provides valuable insights into pricing decisions, operating expenses, sales targets, and expansion opportunities.
In this comprehensive guide, we will explore break-even analysis through a practical SME case study, explain the important financial formulas, demonstrate real-world calculations, and discuss how business owners can use the results to make better financial decisions.
Whether you operate a manufacturing company, retail business, consultancy, restaurant, digital agency, or service-based organization, understanding break-even analysis can help you build a stronger financial foundation.
Let’s understand how it works.
1. What Is Break-Even Analysis?
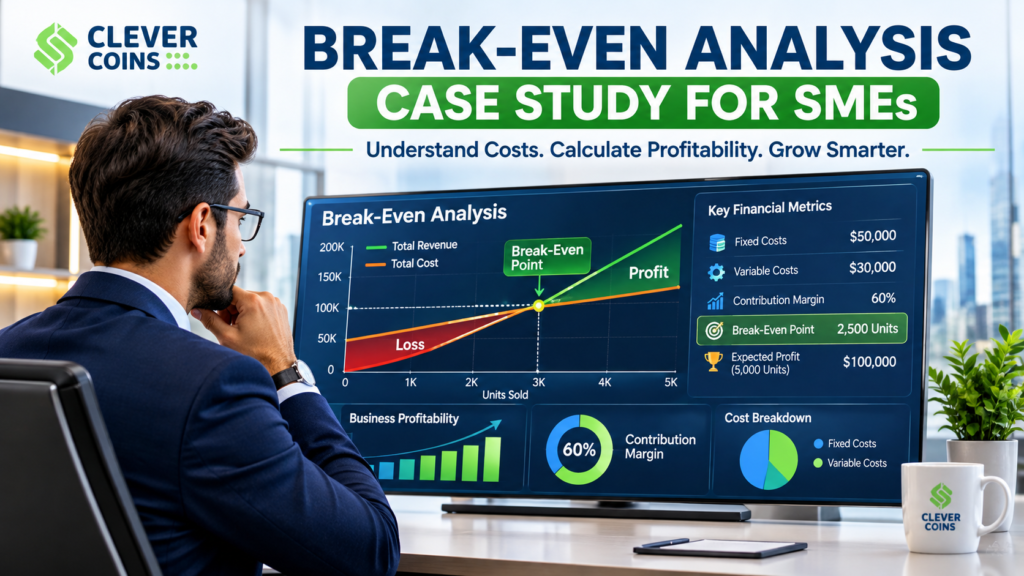
Break-even analysis is a financial calculation used to determine the level of sales at which a business’s total revenue becomes equal to its total costs.
At this point, the business neither makes a profit nor experiences a loss.
In simple terms:
When revenue is lower than total costs, the business operates at a loss.
When revenue equals total costs, the business reaches its break-even point.
When revenue exceeds total costs, the business generates an operating profit, assuming the costs included in the analysis are complete.
The break-even point is particularly important for SMEs because smaller businesses often operate with limited financial resources, tighter cash-flow margins, and less flexibility to absorb unexpected expenses.
For example, imagine a small manufacturing company that spends ₹3,00,000 every month on rent, salaries, utilities, equipment, and other operating expenses.
If the company earns ₹200 in contribution margin from every product sold, it must sell 1,500 products to cover its fixed expenses.
Selling fewer products could result in an operating loss, while selling more could generate an operating profit.
This is the basic principle behind break-even analysis.
According to the U.S. Small Business Administration, break-even analysis helps businesses evaluate startup viability, estimate sales requirements, understand financial risks, and prepare business plans for potential lenders and investors.
2. Why Is Break-Even Analysis Important for SMEs?
SMEs frequently face financial challenges that can affect their long-term sustainability.
Some businesses struggle with increasing operating expenses, while others experience inconsistent sales, poor pricing decisions, or unexpected increases in production costs.
Break-even analysis helps business owners understand the relationship between these factors.
Here are the major reasons why it matters.
2.1 Understanding the Minimum Sales Target
Every business needs to generate sufficient revenue to cover its operating costs.
However, many SME owners establish monthly sales targets based on expectations rather than actual financial calculations.
Break-even analysis provides a more logical starting point.
It helps determine:
How many products must be sold every month.
How much revenue must be generated.
Whether the current sales target is financially realistic.
How far actual sales are from profitability.
Instead of randomly targeting higher sales, business owners can establish measurable financial objectives.
2.2 Improving Pricing Decisions
Pricing products and services incorrectly can significantly affect profitability.
If an SME sets prices too low, its contribution margin may become insufficient to cover fixed costs.
If prices are unnecessarily high, the business may lose customers to competitors.
Break-even analysis allows business owners to understand how different selling prices influence the number of sales required to cover expenses.
It helps answer questions such as:
Can we reduce our selling price without creating financial losses?
How much should we charge to maintain a reasonable contribution margin?
Will a discount campaign increase overall profitability?
Should we increase prices because of rising production expenses?
2.3 Controlling Operating Expenses
Many SMEs accumulate expenses gradually.
These may include additional employees, office rent, software subscriptions, transportation, marketing expenses, maintenance, and administrative costs.
Although individual expenses may appear manageable, their combined impact can increase the break-even point significantly.
Break-even analysis makes this relationship visible.
When fixed expenses increase, the business must generate more contribution to reach profitability.
This encourages management to review unnecessary expenses and identify opportunities for cost optimization.
2.4 Supporting Business Expansion
Business expansion generally requires additional investment.
An SME may consider opening a new branch, purchasing equipment, hiring employees, increasing production capacity, or entering a new geographical market.
However, expansion also increases financial commitments.
Before approving an investment, management can calculate the additional sales required to recover the increased costs.
For example, if opening a new branch increases monthly fixed costs by ₹1,00,000 and the business earns ₹200 contribution per additional unit sold, the company must generate 500 additional unit sales each month to cover those additional fixed costs.
This calculation helps management evaluate whether expansion is financially practical.
2.5 Improving Financial Planning
Break-even analysis supports budgeting and financial forecasting.
It allows business owners to compare expected sales with the minimum revenue required to cover expenses.
It can also be used alongside:
Monthly cash-flow forecasts.
Operating budgets.
Profit and loss statements.
Sales forecasts.
Investment plans.
Financial risk assessments.
The result is a more structured approach to financial management.
2.6 Building Investor and Lender Confidence
Investors and lenders generally want to understand how a business generates revenue, manages expenses, and plans to achieve profitability.
A well-prepared break-even analysis demonstrates that management understands its cost structure and sales requirements.
It can strengthen a business plan by providing a measurable financial benchmark.
However, break-even analysis alone does not guarantee funding or prove that a business will succeed. It should be supported by realistic market research, cash-flow projections, and operational planning.
3. Understanding the Three Main Components of Break-Even Analysis
Before calculating the break-even point, SME owners must understand three essential financial components.
These are fixed costs, variable costs, and selling price.
3.1 Fixed Costs
Fixed costs are business expenses that generally remain unchanged within a particular operating range, regardless of short-term changes in production or sales volume.
Even if a business sells fewer products during a particular month, many fixed expenses still need to be paid.
Common examples include:
Office or factory rent.
Permanent employee salaries.
Insurance premiums.
Equipment depreciation.
Software subscriptions.
Property-related expenses.
Certain administrative expenses.
Fixed contractual service charges.
For example, consider a small manufacturing company with the following monthly expenses:
| Expense | Monthly Cost |
|---|---|
| Factory rent | ₹60,000 |
| Permanent staff salaries | ₹1,20,000 |
| Electricity base charges | ₹10,000 |
| Software and administration | ₹15,000 |
| Equipment depreciation | ₹25,000 |
| Insurance and other expenses | ₹20,000 |
| Maintenance contracts | ₹30,000 |
| Total fixed costs | ₹2,80,000 |
The company must account for these expenses even when its monthly production decreases.
Remember that fixed costs are fixed only within a relevant period and operating capacity. Rent may increase when a lease is renewed, and additional employees may be required when production expands.
3.2 Variable Costs
Variable costs change according to the level of production, sales, or service delivery.
When a company produces more units, its total variable expenses generally increase.
Examples include:
Raw materials.
Product packaging.
Direct production labor paid per unit.
Sales commissions.
Shipping expenses.
Transaction charges.
Production-related consumables.
Outsourced work charged per project.
Suppose a manufacturer spends ₹300 to produce and deliver one product.
This ₹300 represents the variable cost per unit.
If the company sells 100 products, total variable costs will be ₹30,000.
If it sells 500 products, total variable costs will increase to ₹1,50,000, assuming the same unit cost.
The distinction between fixed and variable costs is essential because an incorrect classification can produce misleading break-even results.
3.3 Selling Price Per Unit
Selling price per unit is the amount a business receives from selling one product or service unit.
For example:
A company sells one product for ₹500.
Its selling price per unit is therefore ₹500.
However, businesses should use the realistic net selling price rather than simply the advertised price.
Consider:
Discounts.
Promotional offers.
Customer rebates.
Sales returns.
Applicable indirect taxes.
Platform commissions.
Other transaction-related deductions.
For an accurate contribution calculation, the selling price and variable costs must be defined consistently.
Businesses should also distinguish revenue from cash received. Credit sales may increase reported revenue without immediately generating cash.
4. What Is Contribution Margin?
Contribution margin is one of the most important concepts in break-even analysis.
It represents the amount remaining from a product’s selling price after deducting its variable cost.
This remaining amount contributes towards covering fixed costs. Once fixed costs are covered, additional contribution generates operating profit.
Example:
A business sells one product for ₹500.
Variable cost per product = ₹300.
Contribution margin per unit = ₹500 − ₹300 = ₹200.
This means every product sold contributes ₹200 towards covering the company’s fixed expenses.
A higher contribution margin generally means fewer units are required to reach the break-even point, assuming fixed costs remain unchanged.
Contribution Margin Ratio
The contribution margin ratio expresses contribution margin as a percentage of selling price.
It helps businesses understand how much of every rupee of sales is available to cover fixed costs and generate profit.
For example:
Selling price = ₹500.
Variable cost = ₹300.
Contribution margin = ₹200.
Contribution margin ratio = ₹200 ÷ ₹500 × 100.
Contribution margin ratio = 40%.
This means that 40% of sales revenue is available to cover fixed expenses and contribute towards operating profit.
5. Break-Even Analysis Formula
The standard break-even formula for a single product is:
Break-Even Point (Units) = Fixed Costs ÷ Contribution Margin Per Unit
Since contribution margin per unit is the selling price minus variable cost per unit, the formula can also be written as:
Break-Even Point (Units) = Fixed Costs ÷ (Selling Price Per Unit − Variable Cost Per Unit)
Where:
Fixed Costs = Total fixed operating expenses.
Selling Price = Revenue received per unit.
Variable Cost = Variable expense incurred per unit.
Contribution Margin = Selling price minus variable cost.
Break-Even Point in Revenue
Sometimes businesses prefer to calculate the break-even point in terms of revenue rather than units.
The formula is:
Break-Even Sales Revenue = Fixed Costs ÷ Contribution Margin Ratio
For example:
Fixed costs = ₹3,00,000.
Contribution margin ratio = 40%.
Break-even sales revenue = ₹3,00,000 ÷ 0.40.
Break-even sales revenue = ₹7,50,000.
The business must therefore generate ₹7,50,000 in monthly sales to cover its fixed and variable costs under the assumptions used.
6. Break-Even Analysis Case Study for SMEs: A Manufacturing Business
Now let’s understand how break-even analysis works through a practical case study.
The following is an illustrative example based on a hypothetical Indian SME.
Company Background
Consider a small manufacturing company called ABC Manufacturing Pvt. Ltd.
The company produces and sells reusable industrial storage containers to distributors and business customers.
During the previous year, the company experienced reasonable sales growth. However, management noticed that increasing sales did not always translate into higher profits.
The company was also considering purchasing additional equipment to increase production capacity.
Before making the investment, management decided to conduct a break-even analysis.
The objective was to understand:
How many products must be sold every month to cover all operating expenses?
What monthly revenue is required to reach break-even?
How much profit can be generated at different sales levels?
How would changes in production costs affect profitability?
How many units must be sold to achieve a specific profit target?
Step 1: Identify Monthly Fixed Costs
The finance team reviewed the company’s monthly operating expenses.
| Fixed Expense | Monthly Amount |
|---|---|
| Factory rent | ₹65,000 |
| Permanent employee salaries | ₹1,25,000 |
| Administration expenses | ₹20,000 |
| Equipment depreciation | ₹30,000 |
| Insurance | ₹10,000 |
| Software and communication | ₹10,000 |
| Total fixed costs | ₹2,60,000 |
For the purpose of this case study, management also identified an additional ₹40,000 in recurring fixed operational commitments.
Therefore:
Total monthly fixed costs = ₹2,60,000 + ₹40,000.
Total monthly fixed costs = ₹3,00,000.
Step 2: Calculate Variable Cost Per Unit
The company calculated its average variable manufacturing and delivery cost per product.
| Variable Expense | Cost Per Unit |
|---|---|
| Raw materials | ₹180 |
| Direct production expenses | ₹55 |
| Packaging | ₹25 |
| Transportation | ₹20 |
| Other variable expenses | ₹20 |
| Total variable cost | ₹300 |
Therefore:
Variable cost per unit = ₹300.
Step 3: Determine the Selling Price
After reviewing competitor prices, customer expectations, and production expenses, management established the selling price at ₹500 per unit.
Therefore:
Selling price per unit = ₹500.
Step 4: Calculate Contribution Margin
Contribution margin = Selling price − Variable cost.
Contribution margin = ₹500 − ₹300.
Contribution margin per unit = ₹200.
This means every product sold generates ₹200 towards covering fixed expenses and subsequently generating operating profit.
Step 5: Calculate the Break-Even Point in Units
Now the company has all the required financial information.
Monthly fixed costs = ₹3,00,000.
Selling price per unit = ₹500.
Variable cost per unit = ₹300.
Contribution margin = ₹200.
Using the break-even formula:
Break-even point = Fixed costs ÷ Contribution margin.
Break-even point = ₹3,00,000 ÷ ₹200.
Break-even point = 1,500 units per month.
This means ABC Manufacturing must sell 1,500 products every month to cover its fixed and variable expenses.
At this level, the business generates neither an operating profit nor an operating loss.
Step 6: Calculate Break-Even Revenue
The company also wants to know how much monthly revenue it must generate.
Contribution margin ratio = ₹200 ÷ ₹500.
Contribution margin ratio = 0.40 or 40%.
Break-even revenue = Fixed costs ÷ Contribution margin ratio.
Break-even revenue = ₹3,00,000 ÷ 0.40.
Break-even revenue = ₹7,50,000 per month.
Therefore, the company must generate ₹7,50,000 in monthly sales to reach its break-even point.
Step 7: Understand the Company’s Financial Position at Different Sales Levels
The finance department prepares three possible sales scenarios.
| Particulars | 1,000 Units | 1,500 Units | 1,800 Units |
|---|---|---|---|
| Sales revenue | ₹5,00,000 | ₹7,50,000 | ₹9,00,000 |
| Variable costs | ₹3,00,000 | ₹4,50,000 | ₹5,40,000 |
| Contribution | ₹2,00,000 | ₹3,00,000 | ₹3,60,000 |
| Fixed costs | ₹3,00,000 | ₹3,00,000 | ₹3,00,000 |
| Operating profit/loss | −₹1,00,000 | ₹0 | ₹60,000 |
The results provide important insights.
Scenario A: Selling 1,000 Units
The company generates ₹5,00,000 in revenue.
However, its contribution is only ₹2,00,000, while fixed costs are ₹3,00,000.
The business therefore experiences an operating loss of ₹1,00,000.
Scenario B: Selling 1,500 Units
The company generates ₹7,50,000 in revenue.
Its total contribution equals its fixed costs.
The business reaches its break-even point.
Scenario C: Selling 1,800 Units
The company generates ₹9,00,000 in revenue.
After deducting variable expenses and fixed costs, it generates an operating profit of ₹60,000.
This illustrates how break-even analysis can help management understand the financial impact of different sales volumes.
Step 8: Calculate the Margin of Safety
The margin of safety indicates how much actual or expected sales can decline before the business reaches its break-even point.
Formula:
Margin of Safety = Actual Sales − Break-Even Sales
Suppose ABC Manufacturing expects to sell 1,800 units per month.
Actual sales = 1,800 units.
Break-even sales = 1,500 units.
Margin of safety = 1,800 − 1,500.
Margin of safety = 300 units.
Margin of safety percentage:
= (300 ÷ 1,800) × 100.
Margin of safety = 16.67%.
This means sales can decline by approximately 16.67% from the expected level before the business reaches its break-even point, assuming all other factors remain unchanged.
A higher margin of safety generally indicates a stronger buffer against unexpected sales declines.
7. Interactive Break-Even Point Visualization
The following model illustrates how changes in fixed costs, selling prices, and variable costs influence the break-even point.
<break-even-calculation>
8. What Does the Case Study Tell Us?
The case study provides several important financial insights.
8.1 Sales Growth Must Be Supported by Contribution
Increasing sales does not automatically guarantee profitability.
If a company increases sales by offering heavy discounts, its contribution margin may decline.
The company might sell more products but still struggle to cover fixed expenses.
SMEs should therefore monitor contribution margin alongside sales revenue.
8.2 Cost Management Directly Influences Profitability
ABC Manufacturing has monthly fixed costs of ₹3,00,000.
Any increase in these expenses requires additional contribution to maintain the same financial position.
Management must evaluate whether new expenses generate sufficient additional sales or operational benefits.
8.3 The Break-Even Point Provides a Measurable Target
Rather than relying on general sales expectations, the company now has a clear monthly target of 1,500 units.
This allows management to coordinate sales, production, procurement, and financial planning.
8.4 Profitability Requires More Than Reaching Break-Even
Breaking even means the business has covered the costs included in the model.
It does not necessarily mean the company has achieved a satisfactory return on investment.
The business should establish additional targets for operating profit, cash flow, debt repayment, and future investment.
9. Sensitivity Analysis: What Happens When Business Conditions Change?
One of the biggest advantages of break-even analysis is the ability to test different business scenarios.
SMEs operate in changing market conditions. Material prices fluctuate, employees receive salary increases, customer demand changes, and competitors introduce new pricing strategies.
Sensitivity analysis helps businesses understand how these changes affect their break-even point.
Let’s examine the ABC Manufacturing case.
Scenario 1: Increase in Selling Price
Suppose the company increases its selling price from ₹500 to ₹550.
Variable cost remains ₹300.
New contribution margin = ₹550 − ₹300.
New contribution margin = ₹250.
Break-even point = ₹3,00,000 ÷ ₹250.
New break-even point = 1,200 units.
The company now needs to sell 300 fewer units to cover its monthly fixed expenses.
However, management must evaluate whether customers will accept the increased selling price and whether competitors offer similar products at lower prices.
Scenario 2: Reduction in Variable Costs
Suppose the company negotiates better raw material prices and optimizes packaging.
Variable cost decreases from ₹300 to ₹280 per unit.
Selling price remains ₹500.
New contribution margin = ₹500 − ₹280.
New contribution margin = ₹220.
Break-even point = ₹3,00,000 ÷ ₹220.
New break-even point = approximately 1,364 units.
Cost optimization reduces the required monthly sales volume.
This demonstrates why procurement efficiency, supplier negotiations, and operational improvements can positively influence profitability.
Scenario 3: Increase in Fixed Costs
Suppose the company purchases new equipment and hires additional employees.
Monthly fixed costs increase from ₹3,00,000 to ₹3,60,000.
Contribution margin remains ₹200.
Break-even point = ₹3,60,000 ÷ ₹200.
New break-even point = 1,800 units.
The company must now sell 300 additional products every month to cover the increased fixed expenses.
Before approving the investment, management should determine whether the additional production capacity can generate sufficient demand and contribution.
Scenario 4: Reduction in Selling Price
Suppose management offers a promotional discount and reduces the selling price from ₹500 to ₹450.
Variable cost remains ₹300.
New contribution margin = ₹150.
Break-even point = ₹3,00,000 ÷ ₹150.
New break-even point = 2,000 units.
The company must sell 500 more units than before to reach break-even.
This illustrates why discounts should be evaluated carefully.
A promotional campaign may increase sales volume, but the increase must be sufficient to compensate for the lower contribution per unit.
Scenario 5: Multiple Changes Occur Together
Real-world business conditions rarely change independently.
Suppose:
Fixed costs increase to ₹3,30,000.
Selling price decreases to ₹480.
Variable cost increases to ₹320.
New contribution margin = ₹480 − ₹320.
New contribution margin = ₹160.
New break-even point = ₹3,30,000 ÷ ₹160.
New break-even point = 2,063 units, approximately.
The business now needs to sell approximately 2,063 units instead of 1,500 units.
This is why SMEs should regularly review their financial assumptions instead of depending on a break-even calculation prepared several months earlier.
10. How Different Types of SMEs Can Use Break-Even Analysis
Break-even analysis is not limited to manufacturing companies.
Businesses operating across different industries can use the same fundamental principles.
10.1 Retail Businesses
Retailers generally deal with several products, each having different selling prices and profit margins.
Break-even analysis helps retailers understand how much total sales revenue is required to cover rent, salaries, inventory-related expenses, utilities, and other operating costs.
For example, a retail clothing store can evaluate whether its average contribution margin is sufficient to support its monthly operating expenses.
It can also compare the profitability of different product categories.
10.2 Restaurants and Cafes
Restaurants often have significant fixed expenses, including rent, salaries, equipment costs, licenses, and subscriptions.
Their variable expenses include ingredients, packaging, delivery commissions, and other order-related costs.
Break-even analysis helps restaurant owners calculate the number of orders they need to generate daily or monthly.
It can also help evaluate menu pricing and the financial impact of food-cost increases.
10.3 Service-Based Businesses
Consultancies, marketing agencies, accounting firms, IT service providers, and other service businesses can calculate break-even points using projects, billable hours, contracts, or monthly client engagements as their measurement units.
For example, a digital marketing agency can calculate the contribution generated by each monthly client after accounting for directly attributable delivery costs.
This helps determine how many clients are required to cover salaries, software, office expenses, and administrative overheads.
10.4 E-Commerce Businesses
E-commerce businesses must consider more than product manufacturing costs.
Their variable expenses may include:
Marketplace commissions.
Payment gateway fees.
Packaging.
Shipping.
Returns and refunds.
Order fulfillment.
Performance-based advertising.
Break-even analysis helps online sellers understand whether their actual net selling price generates sufficient contribution after order-related costs.
10.5 Startups
Startups often face uncertainty because they have limited historical sales data.
A break-even analysis can help founders estimate the sales volume needed to support their initial business model.
It can also be used to compare different pricing structures, staffing plans, and operating models.
However, startup projections should be treated as assumptions that require regular validation against actual market demand.
11. Break-Even Analysis for Businesses Selling Multiple Products
The basic break-even formula is easiest to apply when a business sells one product or a standardized service.
However, many SMEs sell multiple products with different prices and variable costs.
For example, a retailer may sell:
Product A with a contribution margin of ₹100.
Product B with a contribution margin of ₹200.
Product C with a contribution margin of ₹300.
In such situations, calculating break-even separately for each product without considering the overall sales mix may produce misleading conclusions.
A weighted average contribution margin can help solve this problem.
Example
Suppose a business has monthly fixed costs of ₹2,00,000.
Its expected sales mix is:
| Product | Sales Mix | Contribution Margin |
|---|---|---|
| Product A | 50% | ₹100 |
| Product B | 30% | ₹200 |
| Product C | 20% | ₹300 |
Weighted average contribution margin:
= (50% × ₹100) + (30% × ₹200) + (20% × ₹300).
= ₹50 + ₹60 + ₹60.
= ₹170.
Weighted average contribution per unit = ₹170.
Break-even composite units = ₹2,00,000 ÷ ₹170.
Approximately 1,177 composite units.
The business should maintain the assumed sales mix when using this result.
If customers start purchasing more low-contribution products and fewer high-contribution products, the overall break-even point will change.
This makes product mix monitoring particularly important for retailers, wholesalers, and diversified manufacturers.