Presumptive Tax Scheme 44AD: Cost, Process, and Timeline Explained
Running a small or medium-sized business in India comes with an endless list of operational demands—managing inventory, negotiating with suppliers, acquiring customers, and maintaining cash flow. For decades, small business owners faced an additional, disproportionate burden: maintaining exhaustive books of accounts, preserving every single expense voucher, and paying hefty fees for statutory tax audits, even when their profit margins were modest.
To eliminate this administrative bottleneck, the Government of India introduced the Presumptive Tax Scheme under Section 44AD of the Income-tax Act, 1961. Furthermore, with India’s landmark transition to the Income-tax Act, 2025 (effective from April 1, 2026, governing Tax Year 2026–27 onward), these presumptive taxation rules have been consolidated and streamlined under Section 58.
Whether you are filing returns for previous financial years under the familiar Section 44AD framework or planning your compliance strategy for Tax Year 2026–27 under Section 58, understanding the exact cost, process, and timeline of this regime can save you tens of thousands of rupees in accounting overhead and protect you from unexpected tax notices.
In this comprehensive guide by CleverCoins, we break down every technical detail, calculation rule, cost structure, step-by-step filing workflow, and statutory deadline associated with the Presumptive Tax Scheme 44AD.
1. What Is the Presumptive Tax Scheme Under Section 44AD (and Section 58)?
Under traditional income tax rules, a business owner must calculate their taxable profit by subtracting legitimate business expenses (rent, salaries, electricity, travel, raw materials, depreciation) from their gross revenue. To substantiate these deductions, the taxpayer must maintain rigorous books of accounts under Section 44AA and, once turnover crosses prescribed thresholds, undergo a mandatory tax audit by a Chartered Accountant (CA) under Section 44AB.
The Presumptive Tax Scheme 44AD turns this model on its head. Instead of tracking every rupee spent and calculating actual net profit, the Income Tax Department allows eligible small businesses to presume their taxable business income at a fixed minimum percentage of their total annual turnover or gross receipts:
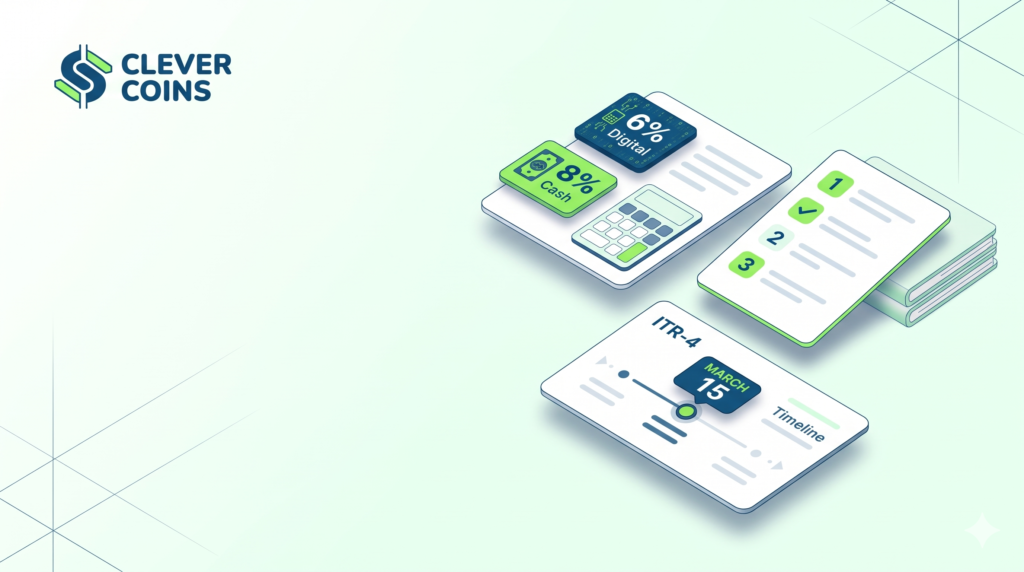
6% of gross receipts/turnover for payments received through prescribed digital or banking channels (account payee cheque, account payee bank draft, electronic clearing system, UPI, NEFT, RTGS, credit/debit cards) on or before the due date of filing the Income Tax Return.
8% of gross receipts/turnover for all other receipts, primarily cash transactions.
Once you declare income at 6% or 8% (or a higher actual profit percentage if you choose), the law deems that all business expenses and depreciation have already been accounted for. You are completely exempted from maintaining detailed accounting ledgers and are relieved from undergoing a statutory tax audit for that business.
The 2026 Regulatory Transition: Section 44AD to Section 58
A critical update every Indian business owner must understand in 2026 is the legislative shift from the Income-tax Act, 1961 to the Income-tax Act, 2025, which came into force on April 1, 2026:
For FY 2025–26 (Assessment Year 2026–27): Returns filed during 2026 continue to be governed by Section 44AD of the Income-tax Act, 1961.
For Tax Year (TY) 2026–27 Onward (April 1, 2026 – March 31, 2027): The presumptive taxation provisions of Sections 44AD (businesses), 44ADA (professionals), and 44AE (goods carriages) have been unified into a single consolidated provision—Section 58 of the Income-tax Act, 2025. While the core turnover limits (₹2 crore / ₹3 crore) and presumptive rates (6% / 8%) remain consistent, Section 58 introduces stricter rules regarding loss set-offs and audit triggers if profits fall below the presumptive threshold.
2. Eligibility Criteria: Who Can Opt for Section 44AD?
Not every business entity or commercial activity qualifies for the Presumptive Tax Scheme. Before adopting Section 44AD (or Section 58), verify that your entity structure, revenue threshold, and business activity meet all statutory requirements.
Eligible Taxpayer Entities
The scheme is strictly restricted to Resident taxpayers in the following three categories:
Resident Individuals (sole proprietors, freelancers running a commercial trade, e-commerce sellers, small retailers).
Resident Hindu Undivided Families (HUFs) carrying on an eligible business.
Resident Partnership Firms (registered or unregistered under the Indian Partnership Act, 1932), explicitly excluding Limited Liability Partnerships (LLPs).
Entities and Taxpayers Excluded from Section 44AD
You cannot opt for Section 44AD if you fall into any of these categories:
Non-Resident Individuals (NRIs), Non-Resident HUFs, or Foreign Partnership Firms.
Limited Liability Partnerships (LLPs).
Private Limited Companies, Public Limited Companies, and One Person Companies (OPCs).
Taxpayers claiming tax holidays or profit-linked deductions under Sections 10AA (SEZ units), 80HH to 80RRB (or corresponding Section 144 / Chapter VIII-C deductions under the 2025 Act) in the same year.
Excluded Business Activities
Even if you operate as a resident individual, HUF, or partnership firm, your nature of business must be eligible. The following activities are barred from Section 44AD:
Specified Professions (Covered under Section 44ADA / Section 58 Sl. No. 3): Legal, medical, engineering, architectural, accountancy, technical consultancy, interior decoration, IT professionals, company secretaries, and notified film artists. (These professionals have their own presumptive scheme at 50% of gross receipts up to ₹50 lakh / ₹75 lakh.)
Commission or Brokerage Income: Insurance agents, real estate brokers, stockbrokers, mutual fund distributors, or affiliate marketers earning primarily via commissions.
Agency Businesses: Any business acting strictly as an authorized agent on behalf of a principal.
Goods Carriage Transport (Covered under Section 44AE / Section 58 Sl. No. 2): Businesses engaged in plying, hiring, or leasing heavy or light goods vehicles.
Crucial Warning for Hybrid Earners: Under Section 58 of the Income-tax Act, 2025, earning even a small amount of commission, brokerage, or agency income alongside your regular business or freelance revenue can disqualify your entire stream from presumptive taxation. Always segregate or evaluate commission streams carefully with a tax advisor.
Turnover Thresholds: ₹2 Crore vs. ₹3 Crore Limit
Your total annual turnover or gross receipts determine whether you qualify:
Standard Turnover Limit: ₹2 Crore. Any eligible business with gross receipts up to ₹2 crore in a financial year can opt for Section 44AD regardless of how much cash they accept.
Enhanced Digital Turnover Limit: ₹3 Crore. To incentivize cashless commerce, the government raised the upper ceiling to ₹3 crore, provided that aggregate cash receipts do not exceed 5% of total turnover or gross receipts during the year. Note that cheques or bank drafts that are not account payee are treated as cash for this 5% calculation.
3. Detailed Cost Breakdown of Presumptive Tax Scheme 44AD
When business owners ask about the “cost” of Section 44AD, they are usually evaluating three distinct financial components:
Government Registration / Application Cost
Actual Income Tax Liability (Your Tax Outflow)
Professional & Compliance Cost (CA / Filing Fees vs. Traditional Accounting)
Let’s examine each cost dimension in complete detail.
A. Government Registration Fee: ₹0 (Zero)
There is no separate registration, license, or application fee to enroll in the Presumptive Tax Scheme. You do not need to apply to the Income Tax Department in advance or obtain a certificate. You simply opt into the scheme directly while filing your annual Income Tax Return (Form ITR-4).
B. Income Tax Liability Calculation (How Much Tax Will You Actually Pay?)
Your tax cost depends on two steps: first, computing your Presumptive Taxable Income (6% or 8% of turnover), and second, applying the Income Tax Slab Rates applicable to your entity and chosen tax regime (New Tax Regime vs. Old Tax Regime).
Step 1: Computing Presumptive Income
Suppose M/s Sharma Electronics (a sole proprietorship) records a total turnover of ₹1,20,00,000 (₹1.20 Crore) in a financial year:
Digital Receipts (UPI, NEFT, Card, Account Payee Cheques): ₹1,00,00,000 (₹1 Crore)
Cash Receipts: ₹20,00,000 (₹20 Lakh)
Since cash receipts (₹20 lakh) are 16.67% of total turnover (exceeding the 5% cash threshold), the business is still well within the ₹2 crore standard limit. Its presumptive income is calculated as:
6% on ₹1,00,00,000 (Digital): ₹6,00,000
8% on ₹20,00,000 (Cash): ₹1,60,000
Total Presumptive Business Income: ₹7,60,000
Even if Sharma Electronics actually earned a net profit of ₹14,00,000 after expenses, the owner only needs to declare ₹7,60,000 as taxable business profit (though they have the option to voluntarily declare a higher profit if needed for bank loan eligibility).
Step 2: Applying Slab Rates (Tax Outflow Scenarios)
Once presumptive profit is computed, it is added to any other income (such as savings bank interest or rental income) to determine total taxable income:
For Resident Individuals & HUFs: Taxed according to standard progressive slab rates. Under the New Tax Regime (default regime with enhanced basic exemption limits and Section 87A tax rebate), an individual whose total taxable income is ₹7,60,000 may pay zero or minimal tax after standard rebates! Even at ₹1.5 crore turnover (100% digital = ₹9,00,000 presumptive profit), the effective tax outflow under the New Tax Regime remains remarkably low—often less than 0.2% to 0.4% of gross turnover.
For Resident Partnership Firms: Unlike individuals, partnership firms do not get basic exemption slabs or Section 87A rebates. A partnership firm pays a flat 30% income tax (plus 12% surcharge if income exceeds ₹1 crore, and 4% Health & Education Cess = 31.2% effective base tax) on its presumptive income.
Important Note for Partnership Firms: Previously, partnership firms could deduct partner remuneration and interest on capital under Section 40(b) from presumptive income; however, subsequent amendments removed this extra deduction—meaning the 6%/8% presumptive profit is the final taxable figure for the firm.
C. Compliance & Professional Cost Comparison: Section 44AD vs. Regular Taxation
The biggest financial advantage of Section 44AD is the dramatic reduction in recurring accounting and audit expenses.
| Cost Component | Regular Business Taxation (Non-Presumptive) | Presumptive Tax Scheme (Section 44AD / Sec 58) | Annual Savings with 44AD |
| Bookkeeping & Accounting Software | ₹18,000 – ₹60,000 / year (full-time/part-time accountant + software) | ₹0 – ₹6,000 / year (basic bank statement & GST sales summary) | ₹15,000 – ₹54,000 |
| Statutory Tax Audit Fee (Form 3CD) | ₹15,000 – ₹45,000 / year (mandatory if audit triggers apply) | ₹0 (Exempt from tax audit under Sec 44AB / Sec 63) | ₹15,000 – ₹45,000 |
| ITR Preparation & Filing Fee | ₹5,000 – ₹15,000 (Complex ITR-3 with Balance Sheet & P&L) | ₹1,500 – ₹5,000 (Simplified ITR-4 Sugam) | ₹3,500 – ₹10,000 |
| Total Annual Compliance Cost | ₹38,000 – ₹1,20,000+ | ₹1,500 – ₹11,000 | Up to ₹1,00,000+ saved |
4. Key Rules, Deductions, and the 5-Year Lock-In Trap
Before opting into Section 44AD, you must understand four non-negotiable statutory rules that govern how deductions, depreciation, advance tax, and exits work.
1. No Separate Business Expense Deductions
When you declare 6% or 8% of turnover, the Income Tax Act presumes that all deductions under Sections 30 to 38 have been fully allowed. You cannot claim separate deductions for:
Shop or office rent
Employee salaries and wages
Electricity, internet, and telephone bills
Business travel, fuel, or repair costs
Interest on business loans
Bad debts written off
What You CAN Still Claim:
Chapter VI-A Deductions (if opting for the Old Tax Regime): Personal tax-saving investments and expenses such as Section 80C (PPF, ELSS, LIC, home loan principal), Section 80D (health insurance premiums), Section 80CCD(1B) (NPS), and Section 80G (donations) are still deductible from your Gross Total Income. (Under the New Tax Regime, most Chapter VI-A deductions are unavailable except employer NPS contributions under 80CCD(2).)
2. Deemed Depreciation Rule
You cannot claim separate depreciation on fixed assets (computers, machinery, commercial vehicles, office furniture). However, for the purpose of calculating capital gains or future depreciation if you ever exit the scheme, the Written Down Value (WDV) of your business assets is calculated every year as if depreciation had actually been claimed and allowed.
3. Single-Installment Advance Tax Concession
Normal businesses with an annual tax liability exceeding ₹10,000 must pay Advance Tax in four quarterly installments (15% by June 15, 45% by September 15, 75% by December 15, and 100% by March 15).Under Section 44AD, you enjoy a major cash-flow relaxation: you only need to pay 100% of your Advance Tax in a single installment on or before March 15 of the relevant financial year. Failing to pay by March 15 attracts nominal interest of 1% per month under Section 234C.
4. The Critical 5-Year Lock-In Rule (Section 44AD(4) / Section 58(7))
This is the single most misunderstood rule in presumptive taxation:
Once you opt for Section 44AD in a particular year, you are expected to continue declaring profits under Section 44AD for the next 5 consecutive assessment years.
What happens if you opt out early? Suppose you declare 8% profit in Year 1 and Year 2, but in Year 3 your actual profit drops to 3% and you decide to file regular books showing 3% profit. The moment you opt out within the 5-year window:
5-Year Ban: You become ineligible to re-enter Section 44AD for the next 5 consecutive years.
Mandatory Bookkeeping & Tax Audit: If your total income exceeds the basic exemption limit, you are compulsorily required to maintain full books of accounts and undergo a CA tax audit for the year you opt out and the subsequent 5 years, regardless of how small your turnover is.
Strategic Takeaway: If your business operates on razor-thin margins (for example, 1.5% to 3% net margin in wholesale distribution or fuel retail) or is currently in a loss-making growth phase, do not blindly opt into Section 44AD just to save audit fees. Declaring 6% or 8% when you only earned 2% means paying tax on phantom profits.