How Mudra Loan Application Impacts Business Growth: The Complete Strategic Playbook for Indian MSMEs
Access to timely, affordable capital has historically been the single biggest dividing line between a micro-enterprise that merely survives and a small business that scales into a regional or national brand. Across India, millions of ambitious shopkeepers, boutique manufacturers, logistics operators, food processors, and service entrepreneurs possess deep operational skill and strong local customer demand—yet hit an invisible growth ceiling the moment they need capital to buy a second machine, stock inventory ahead of peak season, or digitize their operations. Traditional commercial lending demanded hard real estate collateral, multi-year audited balance sheets, and heavy upfront equity that grassroots founders simply did not possess.
The launch and continuous evolution of the Pradhan Mantri Mudra Yojana (PMMY) fundamentally altered this equation. Far more than a passive government credit scheme, a well-structured Mudra loan application acts as a strategic catalyst that reshapes a business’s balance sheet, supply chain bargaining power, operational capacity, and long-term creditworthiness. With cumulative sanctions surpassing 60.36 crore loan accounts worth over ₹43.34 lakh crore as of September 2026, and the introduction of the Tarun Plus tier expanding collateral-free financing up to ₹20 lakh, understanding how a Mudra loan impacts business growth is essential for every founder building in India today.
At CleverCoins, we work closely with micro, small, and medium enterprises (MSMEs) across tax compliance, financial modeling, and institutional credit readiness. In our advisory experience, entrepreneurs who treat a Mudra loan application merely as emergency cash relief capture only a fraction of its value. Those who align their application with unit economics, cash-flow velocity, and staged capacity expansion turn formal credit into a compounding growth engine. This comprehensive guide examines every mechanism through which a Mudra loan application transforms business performance, breaks down the four-tier capital ladder, and outlines how to structure your application for maximum approval odds and return on investment.
Understanding the Core Architecture of PMMY and Why It Matters for Growth
To evaluate how a Mudra loan impacts business growth, founders must first understand what makes PMMY structurally distinct from conventional business term loans and overdraft facilities. Established under the principle of “Funding the Unfunded,” the Pradhan Mantri Mudra Yojana provides institutional credit to non-corporate, non-farm income-generating enterprises across manufacturing, trading, and services—as well as activities allied to agriculture such as dairy, poultry, beekeeping, fishery, and agro-processing.
Crucially, MUDRA (Micro Units Development & Refinance Agency Ltd.) does not lend directly to entrepreneurs across a retail counter. Instead, it operates as a refinance and credit-guarantee ecosystem working through Member Lending Institutions (MLIs), including Public Sector Banks, Private Sector Commercial Banks, Regional Rural Banks (RRBs), Small Finance Banks (SFBs), Microfinance Institutions (MFIs), and Non-Banking Financial Companies (NBFCs).
The Four-Tier Capital Progression Ladder
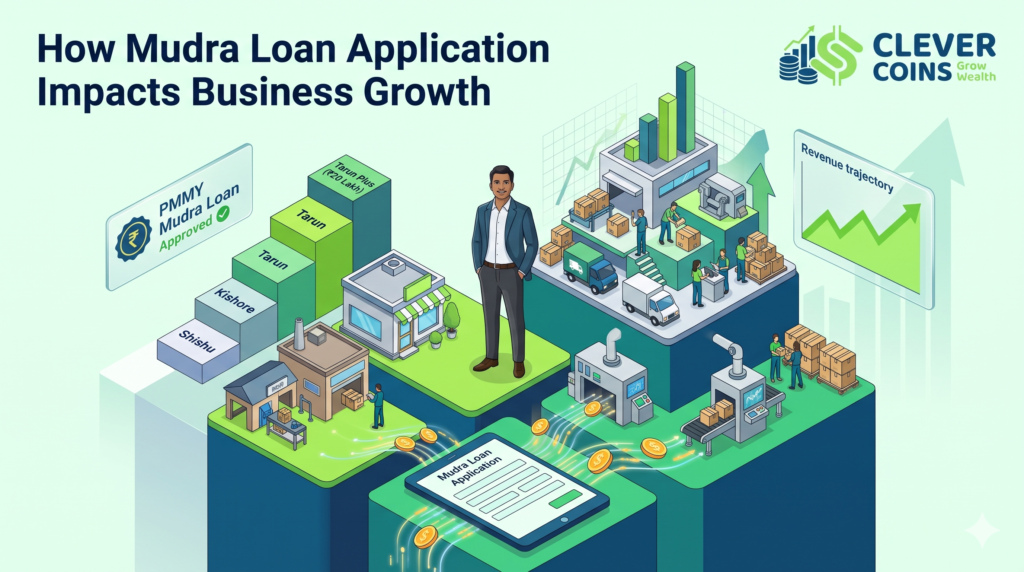
Unlike rigid one-size-fits-all loans, PMMY is engineered around the lifecycle stage of a growing business. Following the Union Budget 2024–25 expansion that became operational in October 2024, Mudra loans span four progressive tiers:
| Mudra Loan Category | Sanction Limit | Primary Business Lifecycle Stage | Typical Use Cases for Growth | Indicative Repayment Tenure |
| Shishu | Up to ₹50,000 | Early-stage startups, micro-vendors, home-based artisans | Initial raw material batches, basic hand tools, point-of-sale devices, micro-inventory | Up to 36–60 months |
| Kishore | ₹50,001 to ₹5,00,000 | Operational micro-units ready to stabilize and expand | Semi-automatic machinery, shop renovation, bulk stock procurement, working capital buffer | Up to 60 months |
| Tarun | ₹5,00,001 to ₹10,00,000 | Established small enterprises scaling production or territory | Commercial vehicles, heavy workshop equipment, multi-outlet expansion, ERP/billing automation | Up to 60–84 months |
| Tarun Plus | ₹10,00,001 to ₹20,00,000 | Proven repeat borrowers who have fully repaid a prior Tarun loan | Factory capacity doubling, automated packaging lines, regional distribution hubs | Up to 84 months |
This four-tier architecture is not accidental. Official Ministry of Finance data reveals a remarkable structural shift in how Indian businesses use the scheme: while Shishu initially dominated loan counts in the scheme’s early years, the share of Kishore and Tarun accounts has surged steadily, and the average Mudra ticket size has nearly tripled from roughly ₹38,000 in FY16 to over ₹1.02 lakh in recent fiscal cycles. Entrepreneurs are not merely taking micro-loans to stay afloat; they are graduating up the Mudra ladder as their enterprises grow.
9 Direct Ways a Mudra Loan Application Impacts Business Growth
When a business owner prepares, submits, and secures a Mudra loan, the impact ripples across nearly every financial and operational metric of the company. Below is a granular analysis of the nine primary growth mechanisms unlocked by PMMY financing.
1. Eliminating the Cost-of-Capital Drag from Informal Moneylenders
Before accessing formal banking channels, a vast majority of Indian micro-entrepreneurs relied on local moneylenders, informal chit funds, or high-interest supplier credit carrying effective interest rates between 24% and 60% per annum. When a small business earns a net operating margin of 18% to 22% but pays 36% annualized interest on borrowed working capital, the enterprise is mathematically trapped—every rupee of profit flows outward to service debt rather than compounding inside the business.
Submitting a Mudra loan application replaces predatory informal debt with regulated institutional pricing. Depending on the lending institution and borrower profile, public sector banks typically price Mudra loans between 9.15% and 12.80% per annum, while private banks and small finance banks generally range from 9% to 18% per annum. Furthermore, many participating lenders offer an additional 0.25% interest rate concession for women entrepreneurs. Cutting financing costs in half immediately expands net profit margins, freeing internal cash reserves that can be reinvested directly into marketing, hiring, or product development.
2. Unlocking Capacity Expansion Without Diluting Equity or Pledging Family Assets
In traditional small business financing, founders face a painful dilemma: either surrender equity to early angel investors or pledge residential property, agricultural land, or family gold as collateral. Both options carry severe drawbacks—equity dilution permanently reduces founder upside, while pledging personal residence assets introduces existential household risk.
Under RBI and PMMY guidelines, Mudra loans up to ₹20 lakh are 100% collateral-free. Lending institutions are strictly prohibited from demanding third-party guarantees or physical property security; instead, loans are backed by the Credit Guarantee Fund for Micro Units (CGFMU) managed by the National Credit Guarantee Trustee Company (NCGTC), with only the assets created out of the loan proceeds hypothecated as primary security. For a growing business, this means you can acquire a CNC machine, a commercial delivery van, a cold-storage unit, or a commercial kitchen setup while retaining 100% ownership and keeping personal family assets completely unencumbered.
3. Accelerating Working Capital Velocity and Cash Conversion Cycles
Even profitable businesses fail when cash gets trapped in unpaid receivables and slow-moving inventory. A common growth bottleneck for MSMEs is turning down large B2B or institutional purchase orders simply because the business lacks the upfront cash to buy raw materials and wait 45 to 60 days for customer payment.
A Mudra loan structured with a working capital component—often paired with a RuPay Mudra Card—provides an on-demand liquidity cushion. Because the Mudra Card operates similarly to a flexible overdraft or cash-credit line for day-to-day operational expenses, the business owner draws funds only when needed and pays interest strictly on the utilized amount for the exact number of days used. This dynamic liquidity shortens the cash conversion cycle, enabling businesses to accept larger orders, fulfill seasonal demand spikes, and maintain uninterrupted production runs.
4. Strengthening Supplier Bargaining Power and Gross Margins
Cash-strapped businesses are forced to buy inventory in small, frequent batches on credit, forfeiting volume discounts and paying higher per-unit prices. Once a Mudra sanction hits your business bank account, your procurement posture changes overnight.
With upfront liquidity, an MSME can:
Negotiate bulk purchase discounts of 5% to 12% from raw material suppliers and wholesale distributors.
Capture early-payment cash discounts (such as a 2% discount for payment within 10 days), which translates to an annualized return far exceeding the Mudra interest rate.
Lock in commodity prices ahead of predictable seasonal inflation—for example, a textile unit buying yarn prior to festival demand or a food processor purchasing grains during harvest windows.
Every percentage point saved on Cost of Goods Sold (COGS) flows straight to the bottom line, improving gross margins without requiring a single rupee of additional customer price increases.
5. Building a Formal Institutional Credit Footprint (CIBIL & CMR Rank)
One of the most underestimated impacts of a Mudra loan application happens after disbursement. Many micro-enterprises operate largely in cash or informal UPI transfers, leaving them “credit invisible” to mainstream banks. When those businesses eventually need ₹50 lakh or ₹2 crore for major expansion, banks reject them due to the absence of a formal repayment track record.
A Mudra loan acts as a financial stepping stone into India’s formal credit bureau ecosystem. Every timely EMI payment is reported to credit bureaus such as TransUnion CIBIL, Experian, Equifax, and CRIF High Mark. Over 12 to 36 months of disciplined repayment:
The founder’s personal CIBIL score strengthens into the 725–780+ bracket.
The enterprise’s CIBIL MSME Rank (CMR) improves, signaling low default risk to commercial underwriters.
The business automatically unlocks eligibility for Tarun Plus (up to ₹20 lakh) and, subsequently, larger CGTMSE-backed MSME term loans, cash credit limits, and export packing credit.
6. Enabling Technology Adoption, Digitalization, and Productivity Gains
Growth in modern Indian commerce increasingly depends on operational efficiency—automated billing, GST-compliant accounting software, e-commerce storefront integration, barcode inventory tracking, and energy-efficient machinery. Yet small business owners frequently postpone technology upgrades because software subscriptions, POS terminals, and modern equipment feel discretionary compared to rent and payroll.
Mudra financing explicitly covers modernization, equipment upgrades, and operational tools. Replacing manual bookkeeping with cloud accounting, installing automated packaging machinery, or upgrading to high-efficiency commercial appliances reduces per-unit labor costs, eliminates human billing errors, and increases output per employee. In manufacturing and food processing units, upgrading a single bottleneck machine funded through a Kishore or Tarun loan regularly boosts daily production capacity by 30% to 75%.
7. Driving Direct and Indirect Job Creation
Scaling a business beyond a solo-operator model requires human capital. Whether hiring skilled machine operators, delivery personnel, store executives, or digital sales associates, payroll expansion is often delayed because new hires take two to three months to become revenue-positive.
By stabilizing working capital and funding productive assets, Mudra loans give founders the financial runway to hire and train staff ahead of peak revenue. Macro-level studies on PMMY consistently demonstrate that Mudra-funded enterprises generate substantial grassroots employment across Tier-2, Tier-3, and rural markets—transforming self-employed individuals into local job creators.
8. Empowering Women-Led Enterprises and Inclusive Entrepreneurship
Roughly 68% of all PMMY loan accounts have been sanctioned to women entrepreneurs, representing millions of women-owned boutiques, beauty and wellness studios, cloud kitchens, tailoring units, diagnostic clinics, retail stores, and agro-processing enterprises. Beyond preferential interest concessions offered by several public and private banks, collateral-free Mudra credit removes the systemic barrier of property ownership—since real estate in many households has historically been held in male family members’ names. Access to independent institutional capital directly translates into higher household income, business formalization, and sustained multi-year enterprise survival.
9. Enforcing Financial Discipline and Compliance Readiness
Surprisingly, the process of preparing a Mudra loan application itself makes a business stronger. To submit a credible application on the JanSamarth portal or at a bank branch, an entrepreneur must organize:
Udyam Registration (official MSME identity)
GST registration and return filings (where applicable)
Six months of clean business bank statements
A structured Project Report / Cash Flow Projection
Going through this documentation exercise forces founders to separate personal household spending from business cash flows, reconcile sales margins, and build realistic monthly revenue forecasts. Even before the loan is sanctioned, the business becomes better governed, audit-ready, and eligible for government tenders and B2B vendor onboarding.
Deep Dive: How Each Mudra Tier Maps to a Specific Growth Strategy
Choosing the wrong loan size can be just as damaging as having no loan at all. Borrowing too little leaves an expansion project half-finished; borrowing excessively burdens early cash flows with unnecessary EMI obligations. Below is how smart founders match their growth objectives to each PMMY category.
Shishu (Up to ₹50,000): Validation and Micro-Asset Seed Capital
Strategic Objective: Transition from informal side-hustle or daily-wage trade into a structured micro-enterprise with zero processing fee burden (banks charge NIL processing fees on Shishu loans).
High-ROI Growth Uses: Purchasing commercial sewing machines, street-food carts with hygienic stainless-steel fittings, smartphone-based POS billing terminals, initial wholesale inventory, or basic salon/repair toolkits.
Growth Benchmark: Use a 12-to-24-month Shishu cycle to establish consistent bank account inflows and build a spotless repayment history that qualifies you for Kishore.
Kishore (₹50,001 to ₹5,00,000): Operational Stabilization and Bottleneck Removal
Strategic Objective: Eliminate the primary operational constraint limiting daily revenue in an already functioning business.
High-ROI Growth Uses: Adding a second production shift, purchasing commercial ovens or packaging units, expanding retail shelf space, stocking high-margin fast-moving SKUs, or launching local digital marketing.
Growth Benchmark: Target an incremental gross profit that covers the monthly Kishore EMI by at least 2.5x to 3x.
Tarun (₹5,00,001 to ₹10,00,000): Commercial Scaling and Multi-Channel Expansion
Strategic Objective: Transform a profitable local micro-unit into a structured small enterprise capable of serving multiple neighborhoods, B2B clients, or regional distributors.
High-ROI Growth Uses: Acquiring dedicated commercial transport vehicles, installing semi-automated manufacturing lines, opening a second retail branch or dark store, and implementing inventory/ERP software.
Growth Benchmark: Maintain clean GST filings, healthy debt-service coverage ratios (DSCR above 1.5), and zero EMI bounces to unlock the highest tier.
Tarun Plus (₹10,00,001 to ₹20,00,000): Industrialization and Regional Dominance
Strategic Objective: Leverage proven creditworthiness to execute major capital expenditure without pledging real estate.
Eligibility Gatekeeper: Unlike Shishu, Kishore, and Tarun, first-time borrowers cannot apply directly for Tarun Plus. It is reserved exclusively for entrepreneurs who have previously availed a Tarun loan (₹5–10 lakh), repaid it in full, and hold a valid Loan Closure Certificate alongside a clean credit profile (typically CIBIL 700+).
High-ROI Growth Uses: Commissioning automated assembly or food-processing machinery, establishing a regional warehouse, fulfilling large corporate/government supply contracts, and scaling workforce capacity.