Common Mistakes in Working Capital Optimization and How to Avoid Them
Every year, thousands of profitable, fast-growing companies run out of cash. On their income statements, revenue is climbing, gross margins look healthy, and net profit shows a comfortable surplus. Yet inside their bank accounts, liquidity is evaporating—forcing founders to delay payroll, pass up bulk supplier discounts, or take on high-interest emergency debt just to keep the lights on.
The culprit behind this financial paradox is almost always poor working capital optimization.
Working capital—defined simply as Current Assets minus Current Liabilities—is the financial oxygen of day-to-day business operations. It funds the gap between paying suppliers for raw materials or services and collecting cash from customers. When managed with discipline, working capital fuels self-funded growth, strengthens creditworthiness, and cushions a business against economic shocks. When mismanaged, it silently traps hundreds of thousands—or crores—of rupees inside unpaid invoices, dusty warehouse shelves, and poorly timed tax or vendor outflows.
In this comprehensive guide, we dissect the most costly mistakes businesses make in working capital optimization, examine the operational and compliance blind spots behind them, and provide step-by-step frameworks to unlock trapped cash across your entire operating cycle.
Understanding the Mechanics of Working Capital Optimization
Before diving into the mistakes, it is critical to distinguish between having working capital and optimizing working capital.
Many business owners assume that a high Current Ratio (Current Assets divided by Current Liabilities) automatically signals financial health. In reality, a Current Ratio of 3.5:1 might indicate severe operational inefficiency—meaning the business is hoarding excessive, slow-moving inventory or failing to collect overdue customer receivables.
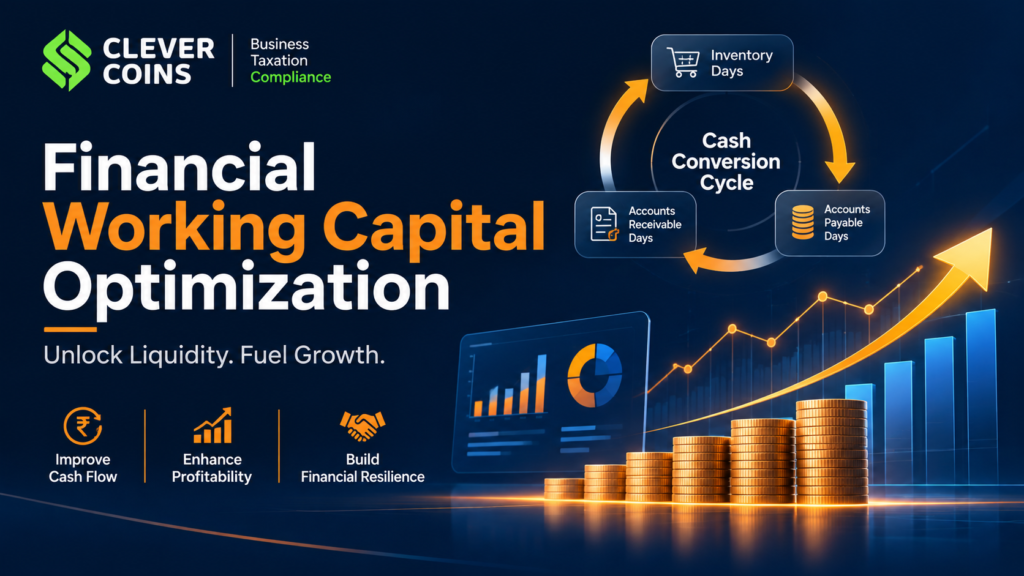
True working capital optimization is the continuous balancing of liquidity, operational efficiency, and profitability. Finance teams measure this balance through the Cash Conversion Cycle (CCC):
Where:
Days Inventory Outstanding (DIO): The average number of days it takes to convert inventory into sales.
Days Sales Outstanding (DSO): The average number of days it takes to collect cash after a sale is made.
Days Payables Outstanding (DPO): The average number of days the company takes to pay its suppliers and vendors.
Every mistake in working capital management stretches DIO or DSO upward, compresses DPO prematurely, or introduces volatility that forces the business to hold idle cash buffers. Let us examine each major pitfall in detail.
Mistake 1: Confusing Accounting Profit with Operating Cash Flow
The Trap
One of the most pervasive errors among founders, non-financial executives, and even mid-sized management teams is treating the Profit & Loss (P&L) statement as a proxy for cash availability. Under accrual accounting, revenue is recognized when an invoice is raised or goods are delivered—not when money hits the bank.
When a business wins a massive new contract, the P&L immediately celebrates the revenue spike. However, fulfilling that order requires upfront cash outlays for raw materials, labor, logistics, and GST/tax obligations weeks or months before the customer settles the bill. Rapid growth without parallel working capital planning creates what corporate finance experts call “overtrading”—growing yourself into a liquidity crisis.
How to Avoid It
Monitor Operating Cash Flow (OCF) Alongside EBITDA: Never review a monthly P&L without a reconciled Statement of Cash Flows and a working capital movement schedule. Track the Cash Conversion Ratio :A healthy business typically converts 70% to 90% of its EBITDA into operating cash; anything consistently below 50% signals severe cash leakage in receivables or inventory.
Model Working Capital Requirements Before Scaling: Whenever you launch a new product line, enter a new geography, or sign an enterprise client with extended payment terms, calculate the incremental working capital required to sustain that revenue tier before committing capital.
Separate Growth Capital from Operating Liquidity: Never fund long-term capital expenditures (CapEx) like machinery, software licenses, or office build-outs using short-term working capital lines or operational cash reserves. Match long-term assets with long-term financing.
Mistake 2: Treating Accounts Receivable as a Sales Afterthought
The Trap
In many organizations, the sales team is incentivized purely on booked revenue, while the finance team is left alone to chase collections months later. Sales representatives routinely offer generous 60-day, 90-day, or even 120-day credit terms to close deals faster—without evaluating the buyer’s creditworthiness or factoring the cost of capital into the pricing.
Furthermore, invoicing workflows are often plagued by friction:
Invoices are sent days or weeks after delivery rather than immediately upon milestone completion.
Purchase Order (PO) numbers, HSN/SAC codes, GSTIN details, or delivery challans contain minor discrepancies, giving corporate accounts payable departments an excuse to reset the 60-day payment clock.
Follow-ups begin only after an invoice becomes overdue, rather than proactively confirming receipt and approval beforehand.
How to Avoid It
Implement Strict Credit Underwriting Before Onboarding: Treat every credit customer like a borrower. Run credit bureau checks, verify GST filing regularity, analyze trade references, and assign tiered credit limits and payment terms based on risk profiles rather than gut feeling.
Tie Sales Commissions to Cash Collection: Align incentives across departments by releasing a portion—or all—of sales commissions only when the invoice is collected, or by applying a margin penalty on deals requiring extended credit beyond standard policy.
Automate Invoice Accuracy and Pre-Due Reminders: Eliminate billing errors through automated ERP validation checks (matching PO, GRN, and tax fields prior to dispatch). Institute a structured collection cadence:
Day 1: Automated invoice dispatch with one-click payment links (UPI, NEFT/RTGS, payment gateway).
7 Days Before Due Date: Friendly “courtesy check” confirming the invoice is approved in the client’s ERP system.
Due Date: Automated payment reminder.
Day 7, 15, and 30 Past Due: Escalating outreach from account management to finance leadership, accompanied by credit holds on new orders.
Deploy Early Payment Incentives Strategically: If your cost of borrowing is 11% per annum, offering a 1.5% discount for payment within 10 days instead of 60 days (a “1.5/10 Net 60” term) effectively yields an annualized return of roughly 11.1% while immediately injecting liquidity and eliminating default risk.
Mistake 3: Hoarding “Just-in-Case” Inventory and Ignoring Dead Stock
The Trap
Supply chain disruptions over the past several years conditioned many procurement and operations managers to over-order raw materials and finished goods “just in case.” While avoiding stockouts is important, unchecked inventory accumulation is one of the fastest ways to paralyze working capital.
Cash locked inside slow-moving or obsolete inventory does not merely earn zero return—it actively costs money through warehouse rent, insurance, material handling, shrinkage, spoilage, and financing interest. Worse, many businesses rely on static reorder points set years ago, ignoring shifts in seasonal demand, SKU profitability, and supplier lead times.
How to Avoid It
Segment Stock Using ABC-XYZ Analysis: Combine value-based ABC classification (A = top 20% of SKUs generating 80% of revenue; C = bottom 50% generating 5% of revenue) with demand-variability XYZ classification (X = steady, predictable demand; Z = erratic, unpredictable demand). Apply tight, automated Just-in-Time (JIT) replenishment for AX items, while shifting CZ items to a strict Make-to-Order or dropship model.
Track Inventory Aging and Enforce Liquidation Triggers: Categorize inventory into 0–30, 31–60, 61–90, and 90+ day aging buckets. Establish non-negotiable rules: any SKU crossing 120 or 180 days without movement must be bundled, discounted, returned to vendors under buyback clauses, or liquidated to convert stagnant stock back into deployable cash.
Integrate Sales & Operations Planning (S&OP): Bridge the communication gap between marketing promotions, sales pipelines, and procurement. When sales forecasts are updated dynamically in real time, procurement stops ordering materials for tapering product lines.
Mistake 4: Mismanaging Accounts Payable—Paying Too Early or Too Late
The Trap
Accounts Payable (AP) optimization is frequently misunderstood as simply stalling vendors as long as possible. In practice, businesses commit two opposite errors:
Paying Too Early: Disbursing cash the moment a vendor invoice arrives—even when 30- or 45-day credit terms are contractually available without penalty. Paying early surrenders free supplier financing and drains cash reserves unnecessarily.
Paying Too Late (and Violating Statutory Timelines): Deliberately stretching vendor payments past agreed terms damages supplier trust, results in lost priority during supply shortages, triggers late-payment interest penalties, and—in jurisdictions like India—creates severe direct tax consequences.
Under Section 43B(h) of the Indian Income Tax Act, payments to registered Micro and Small Enterprises (MSMEs) must be made within 15 days (where no written agreement exists) or within a maximum of 45 days (where a written agreement exists). If a business fails to pay an MSME supplier within this statutory window, the entire expense is disallowed as a tax deduction in that financial year, inflating taxable profit and creating an immediate cash tax outflow.
How to Avoid It
Segment Suppliers by Strategic Importance, Discount Opportunity, and Statutory Status: Flag all MSME Udyam-registered vendors in your ERP master data with automated alerts at Day 10 and Day 35 so you never breach Section 43B(h) timelines.
Schedule Payment Runs to Match Credit Terms: Replace ad-hoc daily check runs with structured weekly or bi-weekly payment batches scheduled precisely on invoice due dates (unless an early-payment discount outweighs your internal cost of capital).
Leverage Dynamic Discounting and Supply Chain Finance (SCF): Rather than stretching suppliers unilaterally, collaborate with fintech platforms or banking partners to offer Reverse Factoring / Supply Chain Finance. Your supplier gets paid early at a low financing rate backed by your credit rating, while your business enjoys extended payment terms (e.g., 60 to 90 days) without straining the vendor relationship.
Mistake 5: Relying on Static Annual Budgets Instead of Rolling Cash Forecasts
The Trap
Many companies prepare a static annual budget in March, file it away, and manage daily cash by glancing at their online banking balance each morning. Checking a bank balance tells you what happened yesterday; it provides zero visibility into the massive GST payment, quarterly advance tax installment, annual insurance renewal, or payroll run due three weeks from Tuesday.
Without forward-looking visibility, finance teams are forced into reactive borrowing—drawing down expensive overdraft facilities at the last minute or holding excessive idle cash in low-yield current accounts out of fear of unexpected shortfalls.
How to Avoid It
Implement a Rolling 13-Week Cash Flow Forecast: The 13-week (one-quarter) direct cash flow model is the gold standard in treasury management. Broken down week by week, it maps expected cash inflows (by specific customer invoice maturity) against committed cash outflows (payroll, rent, vendor runs, tax liabilities, loan EMIs). Every Monday, the past week is reconciled against actuals, and Week 14 is added—giving leadership a continuous, high-resolution 90-day liquidity radar.
Run Stress-Test Scenarios: Model “what-if” scenarios inside your cash forecast: What happens to our cash runway if our top two customers delay payment by 30 days? What if raw material costs spike by 12%? What if sales dip 15% next quarter? Having pre-planned triggers prevents panic decisions.
Sweep Idle Cash Automatically: Use bank auto-sweep facilities or overnight liquid mutual funds to ensure surplus cash sitting in current accounts earns yield daily while remaining instantly accessible when payment runs execute.
Mistake 6: Ignoring Tax, Input Credit, and Regulatory Liquidity Traps
The Trap
Tax compliance is rarely viewed through the lens of working capital optimization, yet inefficient tax administration routinely locks up millions in working capital. Common leaks include:
Blocked or Delayed Input Tax Credit (ITC): Failing to reconcile purchase registers with GSTR-2B every month means businesses pay GST in cash even when eligible input credits exist, simply because non-compliant vendors failed to file returns on time.
Unclaimed Tax Refunds: Exporters and businesses operating under inverted duty structures often leave GST refunds or TDS receivables sitting uncollected for quarters due to incomplete documentation.
Miscalculated Advance Tax Installments: Overestimating quarterly profits leads to excess advance tax outflows that remain trapped with tax authorities until assessment, while underestimating triggers punitive interest under Sections 234B and 234C.
How to Avoid It
Enforce Vendor GST Compliance Clauses: Link vendor payment releases—specifically the GST component of vendor invoices—to the reflection of those invoices in your GSTR-2B portal. This protects your cash flow and incentivizes supplier compliance.
Institutionalize Monthly Tax & Refund Audits: Treat tax refund claims (such as zero-rated export LUT refunds or excess TDS credits) with the same urgency as overdue customer receivables. Assign clear monthly KPIs to your tax advisory team to minimize refund turnaround time.
Align Advance Tax Projections with Rolling Forecasts: Recompute quarterly advance tax obligations using actual year-to-date numbers and your updated rolling forecast rather than relying on last year’s baseline.
Mistake 7: Operating in Departmental Silos Without Working Capital KPIs
The Trap
Working capital spans every corner of a business, yet almost nobody owns it holistically:
Procurement celebrates negotiating a 4% unit price discount by ordering a 9-month supply of raw materials—unaware that the resulting storage and financing costs wipe out the savings twice over.
Sales celebrates signing a high-volume distributor on 90-day open credit—unaware that the company borrows at 12% to fund that receivable.
Production runs long batch sizes to maximize machine utilization—creating mountains of finished goods that sit unsold for months.
When each department optimizes its own narrow metric in isolation, enterprise-wide working capital deteriorates.
How to Avoid It
Establish a Cross-Functional Working Capital Committee: Bring together heads of Finance, Sales, Procurement, Operations, and Supply Chain once a month to review CCC metrics, aging receivables, slow-moving inventory, and upcoming cash commitments.
Embed Working Capital Metrics into Departmental Scorecards:
Sales: Net Margin after Cost of Credit, DSO by territory/account manager, and Bad Debt %.
Procurement: Total Cost of Ownership (TCO), DPO optimization, and Supplier Lead-Time Reliability.
Operations: Inventory Turnover Ratio, DIO, and Obsolete Stock %.
Educate Non-Financial Leaders on the Cost of Capital: Run practical internal workshops showing department heads how shaving just 5 days off the Cash Conversion Cycle translates directly into freed-up cash for R&D, marketing, and bonuses.
Mistake 8: Relying on Mismatched or Rigid Financing Structures
The Trap
Even well-run businesses experience seasonal working capital spikes—such as building inventory ahead of festive quarters or funding large project milestones. A frequent mistake is relying on a single rigid overdraft facility or high-cost merchant cash advances rather than structuring a tailored working capital stack.
Additionally, many businesses fail to negotiate covenant terms, drawing power calculations, or collateral requirements with their lenders, leaving approved credit lines underutilized because stock or receivable statements are submitted late or formatted poorly.
How to Avoid It
Match Financing Instruments to Asset Cycles:
Invoice Discounting / Factoring: Ideal for unlocking immediate cash (up to 80–90% of invoice value) from creditworthy B2B receivables without adding traditional term debt.
Cash Credit (CC) / Working Capital Demand Loans (WCDL): Best suited for fluctuating day-to-day inventory and operational cycles.
Letter of Credit (LC) / Trade Credit: Effective for domestic and international procurement, extending payable timelines while reassuring suppliers.
Automate Bank Stock and Receivable Statements: Maintain real-time ERP reporting so monthly Drawing Power (DP) statements are submitted accurately and on time, ensuring maximum credit line availability and avoiding penal interest charges.
Benchmark Borrowing Costs Annually: Review interest spreads, processing fees, and bank charges every 12 months. As your financial discipline and CCC improve, leverage stronger financial ratios to negotiate lower interest rates or collateral release.
Diagnostic Comparison: Reactive vs. Optimized Working Capital Management
| Dimension | Reactive / Mistake-Prone Approach | Optimized Working Capital Approach |
| Primary Focus | P&L revenue growth and bank balance checks | Cash Conversion Cycle (CCC) and Operating Cash Flow |
| Credit Policy | Ad-hoc terms granted by sales reps to close deals | Standardized credit scoring, automated limits, and DSO targets |
| Invoicing & Collections | Batch billing post-delivery; chasing after due dates | Automated instant e-invoicing; proactive pre-due reminders |
| Inventory Strategy | “Just-in-case” bulk buying; static reorder points | ABC-XYZ segmentation, S&OP integration, and aging liquidation |
| Vendor Payments | Paying immediately upon receipt or stalling blindly | Due-date batch scheduling, MSME 43B(h) compliance, and SCF |
| Cash Forecasting | Static annual budget updated once a year | Rolling 13-week direct cash forecast with scenario modeling |
| Tax & Compliance | Year-end reconciliations; idle ITC and delayed refunds | Monthly GSTR-2B matching, timely refund tracking, dynamic tax planning |
| Governance | Siloed departments optimizing conflicting metrics | Cross-functional Working Capital Committee with shared KPIs |
A 90-Day Action Plan to Optimize Your Working Capital
Transforming working capital performance does not require a multi-year ERP overhaul. By executing a disciplined 90-day sprint, most small and mid-sized enterprises can unlock 15% to 25% of trapped liquidity directly from existing operations.
Days 1–30: Diagnose and Stop the Bleeding
Calculate Your Baseline CCC: Compute exact DSO, DIO, and DPO figures over the past four quarters and benchmark them against industry peers.
Audit Top 20 Overdue Receivables: Identify every invoice past 30 days, resolve billing disputes immediately, and initiate executive-level collection calls.
Flag Non-Moving Inventory: Pull a complete inventory aging report and launch targeted clearance promotions or vendor return negotiations for stock older than 120 days.
Verify MSME Vendor Compliance: Audit your vendor master list to ensure all Udyam-registered suppliers are mapped to 15/45-day payment schedules.
Days 31–60: Build Visibility and Tighten Controls
Launch a Rolling 13-Week Cash Forecast: Implement a weekly cash inflow/outflow tracker reviewed every Monday morning by finance and leadership.
Revise Credit Onboarding & Billing SOPs: Mandate credit checks for all new B2B clients, enforce PO-to-invoice validation before dispatch, and activate automated payment reminders.
Rationalize Payment Runs: Consolidate vendor disbursements into scheduled weekly cycles aligned precisely with contractual due dates.
Days 61–90: Institutionalize and Scale Efficiency
Align Departmental Incentives: Introduce DSO and inventory turnover KPIs into sales, procurement, and operations scorecards.
Evaluate Supply Chain Finance & Treasury Tools: Explore invoice discounting, dynamic discounting platforms, or automated sweep accounts to maximize yield and liquidity flexibility.
Establish Monthly Working Capital Reviews: Lock in a recurring monthly governance cadence to track CCC trends, celebrate cash-release milestones, and refine forecasts.