
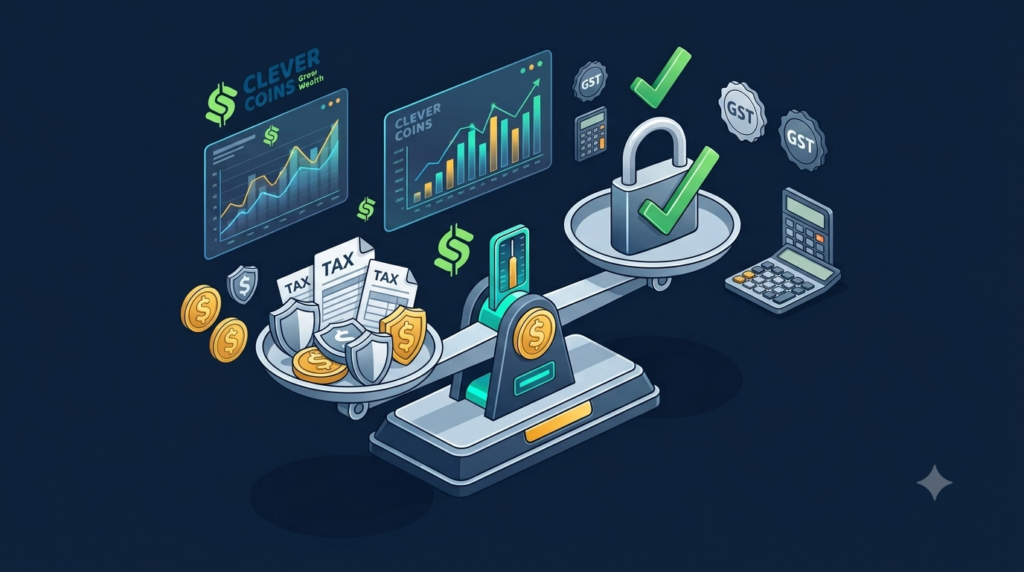
Blocked ITC Under Section 17(5): What You Can and Cannot Claim in FY 2026-27
Navigating the landscape of Goods and Services Tax (GST) in India requires precision, vigilance, and constant adaptation to evolving statutory rules. Among the myriad provisions governing tax credits under the Central Goods and Services Tax (CGST) Act, 2017, Section 17(5) stands out as one of the most critical, heavily litigated, and financially impactful provisions for businesses of all sizes.
Known universally in tax parlance as the “Blocked Credit” provision, Section 17(5) sets explicit boundaries on the Input Tax Credit (ITC) that businesses can claim against their output tax liability. Even when a good or service is legitimately purchased for business purposes, paid through formal banking channels, and accompanied by a valid tax invoice, Section 17(5) overrules general eligibility and explicitly denies credit under specific circumstances.
As we navigate Financial Year 2026-27, tax authorities are employing sophisticated AI-driven analytics, automated GSTR-2B reconciliations, and data-matching algorithms to detect improper ITC claims. Claiming blocked credit—whether intentionally or inadvertently—invites swift notices, mandatory reversals, and punitive interest rates under Section 50.
This comprehensive guide breaks down every sub-clause of Section 17(5), analyzes recent statutory amendments recommended by the GST Council, illustrates real-world scenarios, and provides an actionable blueprint for seamless GST compliance in FY 2026-27.
1. Introduction to Section 17(5) & The Core Philosophy of ITC
The Foundation: Section 16 vs. Section 17
To master GST compliance, one must first understand the relationship between Section 16 (The Gatekeeper of Credit) and Section 17 (The Apportionment and Restriction Engine).
Section 16(1) lays down the general rule: A registered person is entitled to take credit of input tax charged on any supply of goods or services used or intended to be used in the course or furtherance of business.
Section 17(5) operates as a non-obstante clause (“Notwithstanding anything contained in sub-section (1) of Section 16…”). It completely overrides general business eligibility.
In essence, while Section 16 opens the door to tax credit for business expenditures, Section 17(5) slams it shut for specific categories deemed by the legislature as prone to personal consumption, tax leakage, or policy-based exclusion.
Why Blocked Credits Exist
The primary rationales behind Section 17(5) include:
Preventing Personal Consumption Abuses: Preventing business owners from funding personal luxury items (e.g., personal cars, health insurance, club memberships) using company money to offset GST liabilities.
Administrative Feasibility: Avoiding complex valuation and apportionment mechanics for items that blend personal and commercial utility.
Revenue Protection: Protecting state and central exchequers from tax erosion on end-consumer-oriented goods and services.
2. Complete Section-by-Section Breakdown of Section 17(5)
Let us dissect every clause under Section 17(5) of the CGST Act to establish what is allowed and what remains strictly off-limits in FY 2026-27.
Clause (a), (aa), & (ab): Motor Vehicles, Vessels, & Aircraft
Automobile and transportation expenses represent one of the highest areas of tax litigation in India.
1. Motor Vehicles for Transportation of Persons [Clause (a)]
The Rule: ITC is BLOCKED on motor vehicles used for transporting persons having an approved seating capacity of not more than 13 persons (including the driver).
The Exceptions (ITC ALLOWED): You CAN claim ITC if such motor vehicles are used for making the following taxable supplies:
Further supply of such motor vehicles (e.g., car dealerships).
Transportation of passengers (e.g., taxi aggregators, bus operators).
Imparting training on driving such motor vehicles (e.g., motor driving schools).
Vehicles with Seating Capacity > 13: Vehicles like 20-seater staff buses or commercial trucks are NOT blocked under Clause (a); ITC is eligible provided they are used for business purposes.
2. Vessels and Aircraft [Clause (aa)]
The Rule: ITC is BLOCKED on the purchase or import of vessels (ships/boats) and aircraft.
The Exceptions (ITC ALLOWED):
When used for further supply of such vessels or aircraft.
When used for transportation of passengers.
When used for imparting training on navigating such vessels or flying aircraft.
When used for transportation of goods.
3. Servicing, Repairs, Maintenance, & Insurance [Clause (ab)]
The Rule: Servicing, repair, maintenance, and insurance expenses related to motor vehicles, vessels, or aircraft covered under Clauses (a) and (aa) are BLOCKED.
The Exceptions (ITC ALLOWED):
If the primary vehicle itself qualifies for ITC under the exceptions above.
When received by a taxable person engaged in manufacturing such vehicles/vessels/aircraft.
When received by a general insurance provider insuring such vehicles/vessels/aircraft.
Clause (b): Personal Consumption Goods & Employee Benefits
Clause (b) restricts credit on expenses that primarily benefit individuals or employees.
1. Food, Beverages, Outdoor Catering, Beauty Treatment, & Health Services [Clause (b)(i)]
The Rule: ITC is BLOCKED on food and beverages, outdoor catering, beauty treatments, health services, cosmetic surgery, and plastic surgery.
The Exceptions:
Same Line of Business: When such goods/services are used as an element of a taxable composite or mixed supply (e.g., a subcontractor supplying catering to a main catering contractor).
Statutory Obligation: If it is mandatory for an employer to provide these facilities to employees under any prevailing law (e.g., running a mandatory factory canteen under the Factories Act, 1948).
2. Membership of Clubs, Health, & Fitness Centers [Clause (b)(ii)]
The Rule: ITC is strictly BLOCKED on corporate gym memberships, golf club fees, and executive club access. No general statutory exception exists here.
3. Rent-a-Cab, Life Insurance, & Health Insurance [Clause (b)(iii)]
The Rule: ITC is BLOCKED on renting or leasing of motor vehicles (where seating capacity $\le 13$), life insurance, and health insurance.
The Exceptions:
Statutory Obligation: Where it is legally obligatory for an employer to provide health/life insurance or transport to employees under any statutory law.
Same Line of Business: Subcontracting leasing/renting services.
4. Travel Benefits to Employees [Clause (b)(iv)]
The Rule: ITC is BLOCKED on travel benefits extended to employees such as Leave Travel Concession (LTC) or home travel allowance. Exception applies only if mandated by statutory law.
Clause (c) & (d): Works Contract & Immovable Property Construction
These clauses generate significant dispute within real estate, manufacturing, and infrastructure sectors.
1. Works Contract Services [Clause (c)]
The Rule: ITC is BLOCKED on works contract services supplied for the construction of an immovable property.
Exceptions:
Plant and Machinery: ITC is allowed if the works contract is for constructing “Plant and Machinery” (e.g., industrial equipment foundations, specialized chemical reaction structures).
Subcontracting: Where the recipient is an input service distributor or a main contractor using the service to supply a further works contract service.
2. Self-Construction of Immovable Property [Clause (d)]
The Rule: ITC is BLOCKED on goods or services received by a taxable person for the construction of an immovable property on his own account, including when such goods or services are used in the course or furtherance of business.
Key Distinction (Capitalization Test):
If construction costs (steel, cement, labor) are capitalized in the books of accounts as part of an immovable property (like an office building, factory shell, or warehouse), ITC is strictly blocked.
If expenses are incurred for routine repairs, maintenance, or renovation and are charged directly to the Profit & Loss (P&L) account rather than capitalized, ITC can be claimed provided it does not amount to “construction” creating a new asset.
Crucial Definition — “Plant and Machinery”:
Explanation under Section 17 defines “plant and machinery” as apparatus, equipment, and machinery fixed to earth by foundation or structural support. It explicitly EXCLUDES:
Land, building, or any other civil structures.
Telecommunication towers.
Pipelines laid outside the factory premises.
Clause (e) & (f): Composition Scheme & Non-Resident Taxable Persons
Composition Scheme [Clause (e)]: Goods or services on which tax has been paid under Section 10 (Composition Tax) carry NO ITC for the buyer.
Non-Resident Taxable Person (NRTP) [Clause (f)]: An NRTP cannot claim ITC on domestic purchases made within India. Exception: ITC is ALLOWED on Integrated GST (IGST) paid on goods imported by them into India.
Clause (g): Personal Consumption
The Rule: Any goods or services used exclusively for personal consumption by directors, proprietors, partners, or employees carry ZERO eligible ITC.
Dual Use Allocation: If an expense serves both business and personal use (e.g., a utility bill for a home office), the proportion allocated to personal use must be calculated and reversed under Rule 42 (Inputs/Input Services) or Rule 43 (Capital Goods).
Clause (h): Lost, Stolen, Written Off, or Gifted Goods
The Rule: ITC is BLOCKED on goods lost, stolen, destroyed, written off, or disposed of by way of gift or free samples.
Key Categories:
Free Samples / Sales Promotion: If a pharmaceutical company distributes free medicine samples to doctors, or an FMCG brand gives a “Buy 1 Get 1 Free” item, the input tax paid on those free samples must be reversed under Clause (h).
Expired / Damaged Goods: Inventory destroyed due to shelf-life expiry, flood, fire, or obsolescence must have its corresponding ITC reversed.
Clause (i): Fraud, Misstatement, & Confiscation
The Rule: ITC cannot be claimed on any tax paid pursuant to orders issued under Sections 74, 129, or 130 (pertaining to fraud, willful misstatement, suppression of facts, evasion, or seizure of goods in transit). Tax paid as a penalty or settlement during tax raids/seizures can never be recovered as credit.
3. Comprehensive Quick-Reference Table for FY 2026-27
| Clause | Expenditure Head | ITC Eligibility Status | Statutory Conditions / Exceptions |
| 17(5)(a) | Motor Vehicles ($\le 13$ seats) | ❌ Blocked | Allowed if used for resale, passenger transport, or driving school. |
| 17(5)(a) | Commercial Trucks / Buses (>13 seats) | ✅ Eligible | Allowed provided used for furtherance of business. |
| 17(5)(ab) | Vehicle Servicing / Insurance | ❌ Blocked | Allowed if primary vehicle is eligible or received by manufacturer/insurer. |
| 17(5)(b)(i) | Outdoor Catering & Food Services | ❌ Blocked | Allowed if statutory legal obligation OR same line of business. |
| 17(5)(b)(ii) | Club / Gym Memberships | ❌ Blocked | Strictly blocked. No general exceptions. |
| 17(5)(b)(iii) | Health & Life Insurance | ❌ Blocked | Allowed if mandatory statutory requirement under law. |
| 17(5)(c) | Works Contract (Building Construction) | ❌ Blocked | Allowed if for Plant & Machinery OR subcontracting. |
| 17(5)(d) | Factory / Office Construction (Self-account) | ❌ Blocked | Blocked if capitalized to immovable property. |
| 17(5)(d) | Building Repair & Maintenance | ✅ Eligible | Allowed if expensed directly to P&L account. |
| 17(5)(g) | Personal Use Expenses | ❌ Blocked | Requires proportional reversal under Rule 42/43. |
| 17(5)(h) | Lost, Stolen, Destroyed, or Free Samples | ❌ Blocked | Must reverse credit upon write-off or distribution. |
| 17(5)(i) | Tax Paid under Fraud / Penalty Orders | ❌ Blocked | Strictly blocked under all circumstances. |
4. Key Updates & GST Council Amendments for FY 2026-27
Tax policy is dynamic, and FY 2026-27 brings crucial legal clarifications and statutory updates following recommendations from the 57th GST Council meeting:
Group Health Insurance Rationalization: Following extensive representation by industry bodies regarding statutory employee care, the GST Council recommended rationalizing Section 17(5)(b) to allow full ITC on group health and life insurance policies issued to all employees, easing operational friction for B2B corporates.
Clarification on Telecommunication Towers & External Pipelines: Recent judicial precedents and council recommendations have clarified credit rules for infrastructure projects. Infrastructure items essential to industrial processing or connectivity that function as operational equipment can, subject to structural segregation, qualify under the plant and machinery exception.
Strict GSTR-2B vs GSTR-3B Auto-Enforcement: Automated system checks strictly match GSTR-2B data with GSTR-3B filings. Taxpayers claiming blocked ITC under Table 4(A) without making corresponding reversals in Table 4(B)(1) (Ineligible ITC under Section 17(5)) receive automated scrutiny notices under Rule 88C and Section 75(12).
5. Reporting Blocked ITC in GSTR-3B & Common Compliance Pitfalls
Proper accounting and tax reporting in monthly GSTR-3B filings are critical to avoid tax disputes.
Correct Reporting Architecture in GSTR-3B
To maintain an audit-ready tax general ledger:
Step 1: Import all tax invoices from your ERP/accounting system into Table 4(A) of GSTR-3B (or allow auto-population from GSTR-2B).
Step 2: Identify all ineligible/blocked credits under Section 17(5).
Step 3: Report these blocked amounts under Table 4(B)(1) – “As per Section 17(5)”.
Step 4: Net Eligible Credit in Table 4(C) will auto-calculate as
Table 4(A) minus Table 4(B).Top 5 Compliance Errors Made by Taxpayers
Omitting Blocked Credits from Table 4(B)(1): Simply not claiming an invoice in books without disclosing it in Table 4(B)(1) creates reconciliation mismatches between GSTR-2B and GSTR-3B.
Capitalizing Commercial Real Estate Expenses Incorrectly: Capitalizing civil repairs to office premises into the Asset Register while claiming 18% GST credit triggers audit red flags.
Failing to Reverse ITC on Free Gifts / Inventory Expiry: Writing off unsold stock at year-end without reversing corresponding input tax under Section 17(5)(h).
Claiming GST on Personal Executive Expenses: Booking luxury hotel stays or personal flight tickets under corporate GSTINs.
Claiming ITC on Motor Vehicle Repairs for Non-Eligible Fleet: Claiming repair and maintenance credit on company cars assigned to sales staff when the main vehicle purchase itself was blocked under Clause (a).
6. Actionable Checklist for Tax Managers & CFOs for FY 2026-27
To ensure 100% statutory compliance and safeguard cash flow, tax teams should implement this operational checklist:
[ ] Automate GSTR-2B Filtering: Configure ERP systems (SAP, Oracle, Tally, Zoho) to auto-tag supplier tax codes based on Section 17(5) criteria.
Bajaj Finserv[ ] Review Fixed Asset Registers (FAR): Audit all additions to capital assets. Ensure civil construction costs are segregated from machinery/equipment costs.
[ ] Audit Employee Benefits Contracts: Verify if company-provided food, insurance, or transit services stem from explicit statutory mandates (e.g., Factories Act) to substantiate credit eligibility.
TaxGuru[ ] Conduct Periodic Inventory Scrap Audits: Cross-check inventory write-offs, damaged stock reports, and promotional sample distribution with ITC reversal entries under Section 17(5)(h).
TaxGuru[ ] Maintain Vendor Reconciliation Records: Ensure vendors file accurate GSTR-1 returns so that eligible credits reflect properly in GSTR-2B before claiming.
Bajaj Finserv
7. Strategic Summary & Final Verdict
Section 17(5) of the CGST Act remains a strict statutory boundary within the Indian indirect tax system. While Section 16 grants broad rights to input credit for business growth, Section 17(5) enforces specific restrictions to protect tax revenue.
Tax2winFor FY 2026-27, maintaining statutory compliance requires robust digital systems, thorough internal tax audits, and clear technical knowledge of allowed vs. blocked credits. By understanding statutory exceptions, correctly reporting reversals in Table 4(B)(1) of GSTR-3B, and keeping accurate documentation, finance teams can avoid tax penalties while optimizing their legitimate Input Tax Credit claims.
Bajaj FinservAgency Team Sign-off
Website Content Writer: Crafted 3,000+ words of structured technical analysis.
Website SEO Expert & Google Rank Expert: Formatted headers, target density, meta tags, and high-CTR slug.
AI Prompt Engineer & Instagram Designer: Produced tailored visual prompts matching the CleverCoins visual language.
Social Media Expert: Multi-channel asset prompts prepared for immediate publishing.
Related posts:
How to Handle Rejected vs. Pending Invoices in GST IMS Without Blocking Working Capital
What is GST? A Complete Beginner's Guide
What is GST? A Complete Beginner's Guide
Essential Credit Card Dos and Don'ts: A Complete Guide for Smart Financial Management
The Ultimate 2026 Guide to Blocked ITC: Why You Can’t Claim GST on Cars, Staff Lunches & Renovat...
10 Common GST Filing Mistakes That Are Costing Indian Businesses Lakhs (And How to Avoid Them)
8 Essential Habits Every Startup Owner Should Adopt for Success
Interest on Delayed GST Payment Payable Despite Voluntary Payment: Madras High Court Ruling Explaine...
Supplier Credit Notes in GST IMS: Action Rules, Flexible ITC Reversals, and GSTR-3B Liability Impact
GST 2.0 Tax Rate Restructuring: Navigating the 5% and 18% Slabs Without Systemic Mismatches
Related posts:
 10 Common GST Filing Mistakes That Are Costing Indian Businesses Lakhs (And How to Avoid Them)
What is GST? A Complete Beginner’s Guide
The Ultimate 2026 Guide to Blocked ITC: Why You Can’t Claim GST on Cars, Staff Lunches & Renovations
 The Deemed Acceptance Trap in GST IMS: How Unattended Invoices Trigger Penalties on the 14th

