
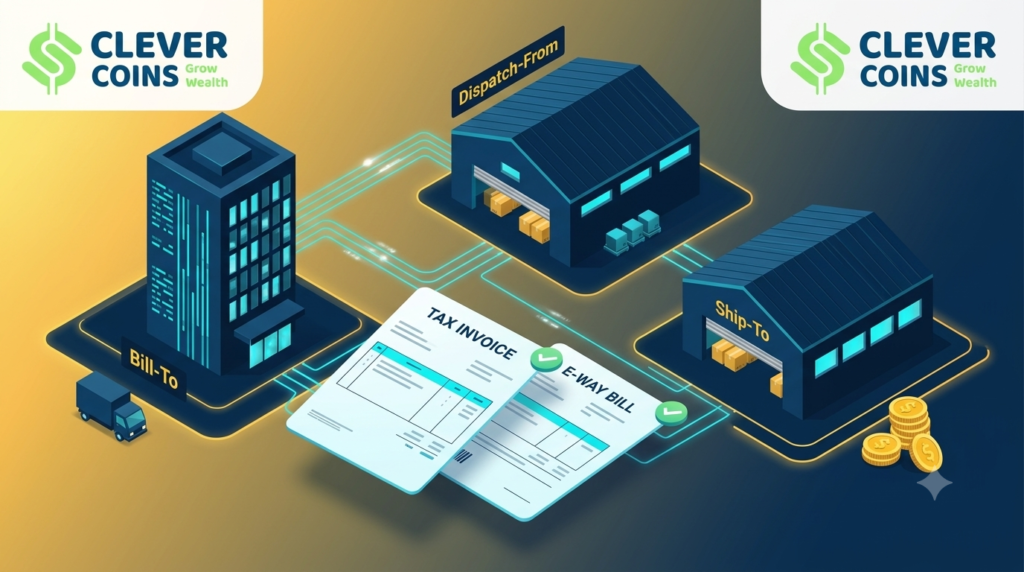
Mastering Bill-To Ship-To & Bill-From Dispatch-From Transactions: The Complete Guide to E-Way Bill and Invoice Structuring
In the modern supply chain landscape, business transactions are no longer simple linear movements of goods from a seller’s single warehouse directly to a buyer’s storefront. Dropshipping, third-party logistics (3PL), centralized procurement offices, contract manufacturing, and multi-state warehouse networks have created complex multi-party trade flows.
Two of the most crucial operational frameworks governing these multi-party movements under Goods and Services Tax (GST) law are Bill-To Ship-To (BTST) and Bill-From Dispatch-From (BFDF) transactions.
While these structures streamline commerce, reduce transit time, and cut freight costs, they present significant tax compliance and documentation challenges. Misaligning invoice line items, issuing conflicting tax details, or misconfiguring E-Way Bills (EWB) can trigger vehicle interception, severe tax penalties under Section 129 of the CGST Act, and blocked Input Tax Credit (ITC) for your buyers.
This definitive guide breaks down the legal foundation, invoicing mechanics, E-Way Bill generation rules, cross-border/interstate complexities, and audit-proofing best practices for Bill-To Ship-To and Bill-From Dispatch-From transaction workflows.
Chapter 1: Foundations of Multi-Party GST Transactions
To understand modern supply chain logistics, one must look at how the GST regime decouples the billing stream (commercial liability) from the dispatch stream (physical movement of goods).
1. Defining “Bill-To Ship-To” (BTST)
A Bill-To Ship-To transaction occurs when a buyer (Party B) purchases goods from a supplier (Party A) and instructs Party A to ship the consignment directly to a third party (Party C).
Bill-To Party (Party B): The entity placing the order and receiving the tax invoice.
Ship-To Party (Party C): The entity receiving the physical delivery of the goods.
Supplier / Bill-From Party (Party A): The vendor issuing the invoice and shipping the goods.
2. Defining “Bill-From Dispatch-From” (BFDF)
A Bill-From Dispatch-From transaction occurs on the seller’s side. It arises when the vendor issuing the invoice (Party A – Billing Branch/Headquarters) dispatches goods from a location other than its billing registered address (e.g., a third-party job worker, a factory, or a regional fulfillment center).
Bill-From Party: The billing establishment whose GSTIN appears as the seller on the tax invoice.
Dispatch-From Location: The physical warehouse, godown, or manufacturing unit from where the goods are loaded onto the vehicle.
Chapter 2: The Legal Framework: Section 10(1)(b) of the IGST Act
The statutory pillar supporting Bill-To Ship-To transactions is Section 10(1)(b) of the Integrated Goods and Services Tax (IGST) Act, 2017.
Section 10(1)(b) IGST Act:
“Where the goods are delivered by the supplier to a recipient or any other person on the direction of a third person, whether acting as an agent or otherwise, before or during movement of goods, either by way of transfer of documents of title to the goods or otherwise, it shall be deemed that the said third person has received the goods, and the place of supply of such goods shall be the principal place of business of such person.”
Key Legal Implications of Section 10(1)(b)
Deemed Receipt: Even though Party B never physically handles the goods, the law deems Party B to have received them at the moment Party A delivers them to Party C. This enables Party B to legally claim Input Tax Credit (ITC) under Section 16(2)(b) of the CGST Act.
Place of Supply (PoS): The Place of Supply for the transaction between Supplier A and Buyer B is determined by Buyer B’s registered location, not where Consignee C is physically located.
Two Distinct Taxable Supplies: Legally, a standard Bill-To Ship-To model consists of two distinct supply contracts executed simultaneously:
Supply 1: Supplier A $\rightarrow$ Buyer B (Billed under Section 10(1)(b)).
Supply 2: Buyer B $\rightarrow$ Recipient C (Billed under standard Place of Supply rules under Section 10(1)(a)).
Chapter 3: Invoicing Mechanics in Bill-To Ship-To Models
Proper invoice structuring prevents double taxation, eliminates audit objections, and allows seamless credit flow across supply chain entities.
Invoice Structure 1: Supplier A to Buyer B
This invoice forms the basis for the physical transit of goods and credit transfer between the original seller and the intermediary buyer.
Supplier Name & GSTIN: Details of Supplier A (Bill-From).
Bill-To Details: Name, GSTIN, and Registered Address of Buyer B.
Ship-To Details: Name, GSTIN (if registered), and Physical Delivery Address of Recipient C.
Tax Determination (IGST vs. CGST/SGST): Based on the state of Supplier A versus the state of Buyer B.
If Supplier A (Maharashtra) bills Buyer B (Gujarat), charge IGST, regardless of where Recipient C is located.
If Supplier A (Maharashtra) bills Buyer B (Maharashtra), charge CGST + SGST, even if Recipient C is in Karnataka.
Invoice Structure 2: Buyer B to Recipient C
This invoice records the commercial transaction between the intermediary buyer and the ultimate recipient.
Supplier Details (Bill-From): Details of Buyer B.
Bill-To Details: Name, GSTIN, and Address of Recipient C.
Ship-To Details: Delivery Address of Recipient C.
Tax Determination: Based on the location of Buyer B relative to Recipient C.
Chapter 4: E-Way Bill Generation Protocols for BTST & BFDF
Generating an E-Way Bill (EWB) for multi-party transactions was historically prone to errors before the GST Network (GSTN) introduced dedicated EWB portal updates specifically for Bill-To Ship-To and Bill-From Dispatch-From options.
E-Way Bill Fields for Bill-To Ship-To Transactions
When generating the E-Way Bill on the portal, select the transaction type as Bill-To Ship-To. The portal will split the recipient section into two distinct segments:
| Section | Field Name | Information to Enter |
| Bill-To | GSTIN & Name | Enter Buyer B’s GSTIN and Name. |
| Bill-To | State | Select Buyer B’s State (This determines the Place of Supply on EWB). |
| Ship-To | GSTIN & Name | Enter Recipient C’s GSTIN (or URP if unregistered) and Name. |
| Ship-To | Delivery Address | Enter Recipient C’s physical location & PIN code. |
Critical Rule on PIN Codes: The distance for E-Way Bill validity calculations is auto-computed based on the PIN codes of the Dispatch-From Location and the Ship-To Location, ensuring that transit time limits accurately reflect physical distance.
E-Way Bill Fields for Bill-From Dispatch-From Transactions
When Supplier A bills out of Head Office (GSTIN Address) but ships from a secondary factory or 3PL warehouse:
Select Transaction Sub-Type as Bill-From Dispatch-From.
Bill-From Section: Enter Supplier A’s registered GSTIN and trade name.
Dispatch-From Section: Enter the actual physical address and PIN code of the dispatch warehouse/factory.
Chapter 5: Operational Use Cases & Case Studies
To apply these rules in day-to-day operations, review these three common enterprise scenarios.
Scenario 1: Three-Party Interstate Transaction
Supplier A: Mumbai, Maharashtra (GSTIN: 27AAAAA0000A1Z5)
Buyer B: Ahmedabad, Gujarat (GSTIN: 24BBBBB0000B1Z2)
Recipient C: Bengaluru, Karnataka (GSTIN: 29CCCCC0000C1Z9)
Execution Workflow:
Invoice 1 (Supplier A $\rightarrow$ Buyer B):
Bill-To: Buyer B (Gujarat).
Ship-To: Recipient C (Karnataka).
Tax Charged: IGST (Supplier A in MH billing Buyer B in GJ).
E-Way Bill Generation (by Supplier A or Buyer B):
Sub-type: Bill-To Ship-To.
Bill-To: Buyer B (GJ GSTIN).
Ship-To: Recipient C (KA PIN Code).
Invoice 2 (Buyer B $\rightarrow$ Recipient C):
Bill-To & Ship-To: Recipient C (Karnataka).
Tax Charged: IGST (Buyer B in GJ billing Recipient C in KA).
Scenario 2: Intra-State Billing with Interstate Physical Delivery
Supplier A: Mumbai, Maharashtra
Buyer B: Pune, Maharashtra
Recipient C: Chennai, Tamil Nadu
Execution Workflow:
Invoice 1 (Supplier A $\rightarrow$ Buyer B): Since both A and B are in Maharashtra, Supplier A charges CGST + SGST, even though the goods are dispatched directly to Tamil Nadu under Section 10(1)(b).
Invoice 2 (Buyer B $\rightarrow$ Recipient C): Buyer B (MH) charges IGST to Recipient C (TN).
Chapter 6: Tax Department Enforcement & Common Pitfalls
During roadside inspection of goods in transit, tax officials verify compliance under Section 68 of the CGST Act. Any discrepancy between physical movement and E-Way Bill details can lead to seizure under Section 129.
1. The “Single E-Way Bill” vs “Dual E-Way Bill” Confusion
Question: Are two E-Way Bills required for a Bill-To Ship-To transaction involving two invoices?
Legal Position: No. As per Circular No. 09/09/2018-GST, one E-Way Bill is sufficient to cover the physical movement of goods from Supplier A to Recipient C. Either Supplier A or Buyer B can generate the E-Way Bill using the Bill-To Ship-To format.
2. Common Errors Leading to Detention & Penalties
A. PIN Code Mismatch
Entering Buyer B’s PIN code in the “Ship-To” field instead of Recipient C’s PIN code alters the auto-calculated distance, leading to invalid EWB validity periods.
B. Absence of Duplicate Invoice in Transit
The driver must carry:
Invoice 1 (Supplier A to Buyer B) with clear Bill-To and Ship-To details.
The generated E-Way Bill. Carrying Invoice 2 without EWB linkage to physical movement often triggers verification delays.
C. Wrong Place of Supply Declaration on Invoice
Charging IGST instead of CGST/SGST because Recipient C is out-of-state (ignoring Buyer B’s in-state registration) leads to improper tax payment and ITC blockage for Buyer B under Section 16.
Chapter 7: Step-by-Step E-Way Bill Generation Guide
Follow this operational checklist to generate E-Way Bills for complex transit arrangements correctly:
Access the official E-Way Bill System portal. Navigate to E-Waybill $\rightarrow$ Generate New. Select Outward under Supply Type and select Sub-Type as Bill-To Ship-To or Bill-From Dispatch-From.
If shipping from a secondary warehouse (BFDF model), update the Dispatch-From address, state, and PIN code to reflect the actual dispatch site while keeping Supplier A’s main GSTIN in the Bill-From field.
In the Bill-To section, enter Buyer B’s GSTIN. The portal auto-populates the registered address. In the Ship-To section, manually enter Recipient C’s GSTIN/URP, delivery address, and destination PIN code.
Enter item descriptions, HSN codes, quantities, and taxable values identical to Invoice 1. Select applicable tax rates (IGST or CGST/SGST based on Supplier A and Buyer B locations).
Enter Transporter ID or Vehicle Number, verify distance auto-computed by the portal, and click Submit to generate the EWB. Hand the printed copy to the transporter.
Chapter 8: Compliance Checklist for Supply Chain & Finance Teams
Before dispatching goods under BTST or BFDF arrangements, verify your documentation against this audit checklist:
[ ] Tax Invoice Verification: Does Invoice 1 explicitly state Supplier A as Bill-From, Buyer B as Bill-To, and Recipient C as Ship-To?
[ ] Place of Supply Check: Is the tax type (IGST vs CGST/SGST) on Invoice 1 determined strictly based on Buyer B’s GST registration state?
[ ] EWB Sub-Type Selection: Is the E-Way Bill sub-type set to Bill-To Ship-To or Bill-From Dispatch-From rather than regular supply?
[ ] PIN Code Accuracy: Does the Ship-To section on the EWB list Recipient C’s exact PIN code?
[ ] Transit Documentation: Is the driver carrying Invoice 1 and the valid E-Way Bill printout?
[ ] ITC Reconciliation: Has Buyer B verified that the ITC claimed on Invoice 1 matches GSTR-2B data before reconciling Invoice 2 sales in GSTR-1?





